PP: The window of profit is the most dangerous when it is open?
If you follow the chemical industry, you may have spotted recent news: propane dehydrogenation(PHD) polypropylene(PP) production has turned profitable. While this sounds unremarkable, it has actually been a rare bright spot across the sector over the past few years.
Until recently, domestic PHD-to-PP businesses were stuck in dire straits. Around 80% of propane feedstock is imported, meaning manufacturers suffer severely from even minor price swings. Meanwhile,downstream PP suffers from oversupply, keeping product prices persistently weak. Squeezed from both ends, the average profit of domestic PHD PP production once slumped to-900 yuan per ton in 2025. The gears governing profit and loss began to shift during the first half of this year. At the start of 2026,geopolitical conflicts in the Middle East pushed up crude oil and propane prices. Oil-based PP production was pushed to the brink of losses, with losses once exceeding 100 yuan per ton. Surprisingly, PHD production, which also relies on imported raw materials, has recently seen a turnaround.
What brought this turning point?
July delivered profit recovery for the PHD industry. Statistics show PHD process profit reached 258 yuan per ton in July, rising 1926 yuan month-on-month from June’s-1668 yuan per ton. Gross profits swung from negative to positive in mid-July,rapidly expanding profit margins. The core driver lies in two mutually reinforcing factors: falling import costs for propane, alongside firm propylene spot prices. Cost-side gains have been fully realized, greatly easing operational pressure for manufacturers. Nevertheless, the industry is characterized by lightning-fast shifts between profit and loss. Once profits emerge, suspended production units rush to restart operations to seize the profitable window. Over the month, numerous domestic PHD facilities have resumed production intensively.
Enterprise | Capacity(10000tons) | Maintenance start date | Production Restart Date |
Zhongjing Petrochemical | Phase1line 1500000 ton | 2026/6/10 | 2026/7/4 |
Zhongjing Petrochemical | Phase1 line2 500,000 tons | 2026/4/1 | 2026/7/8 |
Luqing Petrochemical | Line1, 150,000tons | 2026/7/2 | 2026/7/24 |
Luqing Petrochemical | Line2, 150,000tons | 2026/7/16 | 2026/7/21 |
Dongming Petrochemical | Single production line, 200,000tons | 2026/7/27 | 2026/8/3 |
Jinneng Chemical | Phase2 line1, 450,000tons | 2026/7/15 | 2026/7/19 |
Jinneng Chemical | Phase2 line2, 450,000tons | 2025/12/31 | 2026/6/11 |
Weifang Shufukang | Line2, 150,000tons | 2026/7/2 | 2026/7/9 |
Tianjin Bohua | Single line,300,000 tons | 2026/3/6 | 2026/8/5 |
As of August 6, the operating rate of the PHD industry has rebounded to 75.43% from the April low of 55%,rising by a total of 20 percentage points. Such a rapid upturn qualifies as a lightning-quick reaction within the capital-intensive chemical sector.
How robust is the current profit recovery?
Entering August, the pace of profit recovery has slowed markedly. On the cost side,higher settlement prices for imported propane have lifted production costs to 7402 yuan per ton, representing a month-on-month increase of 285 yuan per ton. Meanwhile, propylene prices have softened synchronously. Squeezed by rising costs and weaker product prices, profit margins have fallen technically from high levels, returning the whole industry to thin-profit territory.
Why this round of improvement is deemed fragile?
First. Inelastic demand. Downstream plastic weaving, injection molding and BOPP film sectors are currently in their off-seasons. End buyers only conduct rigid replenishment purchases with no intention of stocking up on bullish expectations. Once supply increases, the short-lived profits driven by production restarts could vanish rapidly.

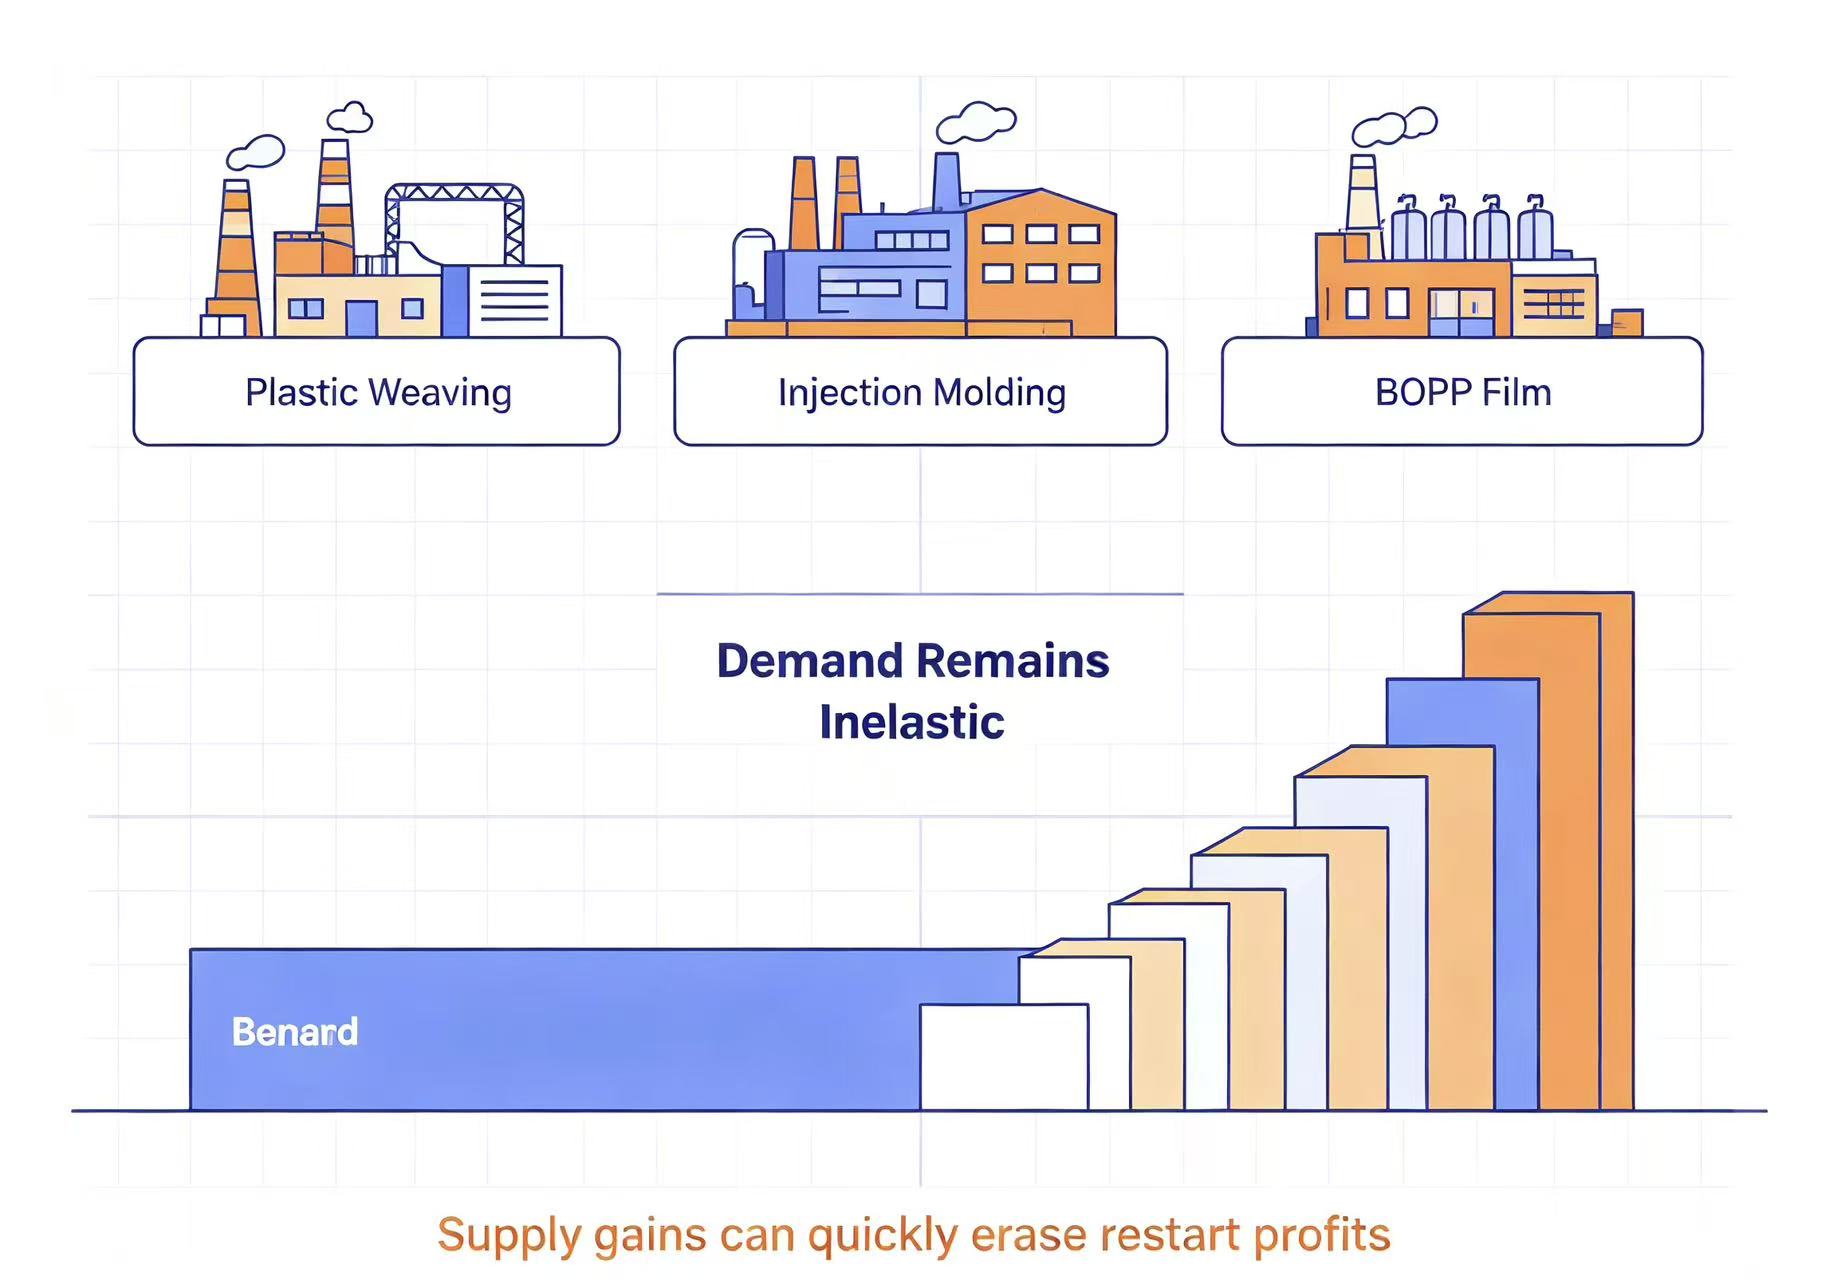
Second. Ample supply elasticity. After profit margins widened, previously idle PHD units have swiftly resumed operation to re-enter the market, leading to fast supply replenishment and fading marginal support for prices.
Third.Looming new capacity pressure. Approximately 4 million tons of new production capacity is scheduled to come online in the second half of the year, which will lock in a loose supply-demand pattern, keeping long term bearish pressure hanging over the market.
It is undeniable that PDH players have returned to profitability, production facilities have restarted, and operational pressure on manufactures has eased temporarily. Nevertheless, it would be premature to regard this as a full trend reversal. Against the backdrop of overcapacity,cyclical profit swings paired with frequent unit shutdowns and restarts may become the new normal for the PHD industry. For polypropylene, the upcoming 4-million-ton new capacity release in the second half of the year will maintain a loose supply-demand structure. Cost-driven gains are only short-term market fluctuations rather than sustained trending opportunities. While this short profit window is worth capturing, caution remains warranted when judging the future market direction.

Your service intention information has been submitted to the platform, we will contact you within 2 working days, please check your email. Thank you.
CPC Index, fully known as China Plastic City Raw Material Price Index, is an important tool to reflect the price trend of plastic raw materials in China Plastic City. The launch of this index aims to provide a reliable reference basis for the majority of plastics industry enterprises to help them better grasp market trends and formulate business strategies.
As the "Industrial Information Operation Situation Index Enterprise" designated by the Ministry of Industry and Information Technology, our company is well aware of the industry's urgent need for accurate and timely plastic price information. Therefore, we officially launched the plastic index in June 2011, providing a professional and authoritative price reference for the majority of plastic enterprises.
The average price is an average price obtained through scientific calculation by our platform according to the price of various plastic products in the whole Chinese market. This average price not only reflects the reference price level of the market as a whole, but also is calculated based on the specific price situation of each sub-brand. In short, the average price is a comprehensive indicator, which reflects the average price level of various plastic products in the Chinese market during a certain period.
By viewing the average price of the market, you can understand the average price trend of various plastic products in a specific period. This helps you to better understand the market dynamics, supply and demand of various products and market competition.
The market reference price refers to the accurate and timely quotation provided by several large traders or agents of a certain brand in China Plastics City. We take the reference price of the brand in Yuyao area on the same day according to the price provided by them. The firm that provides the price is listed as the index gathering firm.
Through the market reference price, you can understand the average price level of the current market, so as to better formulate purchasing, sales and other business strategies. At the same time, the market reference price is also an important basis for users to analyze and forecast the market, helping them grasp the market trend and find business opportunities.
The reference price rise and fall list is a tool to rank the price rise and fall of various categories of plastic products under the market reference price. It tracks and compares the price changes of products under various categories of symbols in different time periods such as week, month and year, and then selects the top 20 with the highest price increase or the top 20 with the highest price decrease to form the price rise list and price fall list respectively.
The reference price rise and fall list provides a practical reference for practitioners in the plastics industry, helping you quickly capture the most volatile products in the market, and providing strong data support for your decision.