Cost, supply, and demand dynamics
How long can PE’s toughness last?
Introduction: In August, the PE market demonstrated strong performance, supported by both high costs and low inventories. Prices did not decline along with the off-season but instead maintained a pattern of fluctuation after an increase. However, the actual transaction volume at the terminal is driven by offering discounts, and the demand-driven force has not yet truly taken effect. As the maintenance facilities are restarted and new production capacity gradually increases, supply pressure is approaching, the market is at a crossroads, with costs providing a floor while supply and demand weaken.
First: Short-term market: Geopolitical premiums have become dull, and pricing has returned to fundamentals.
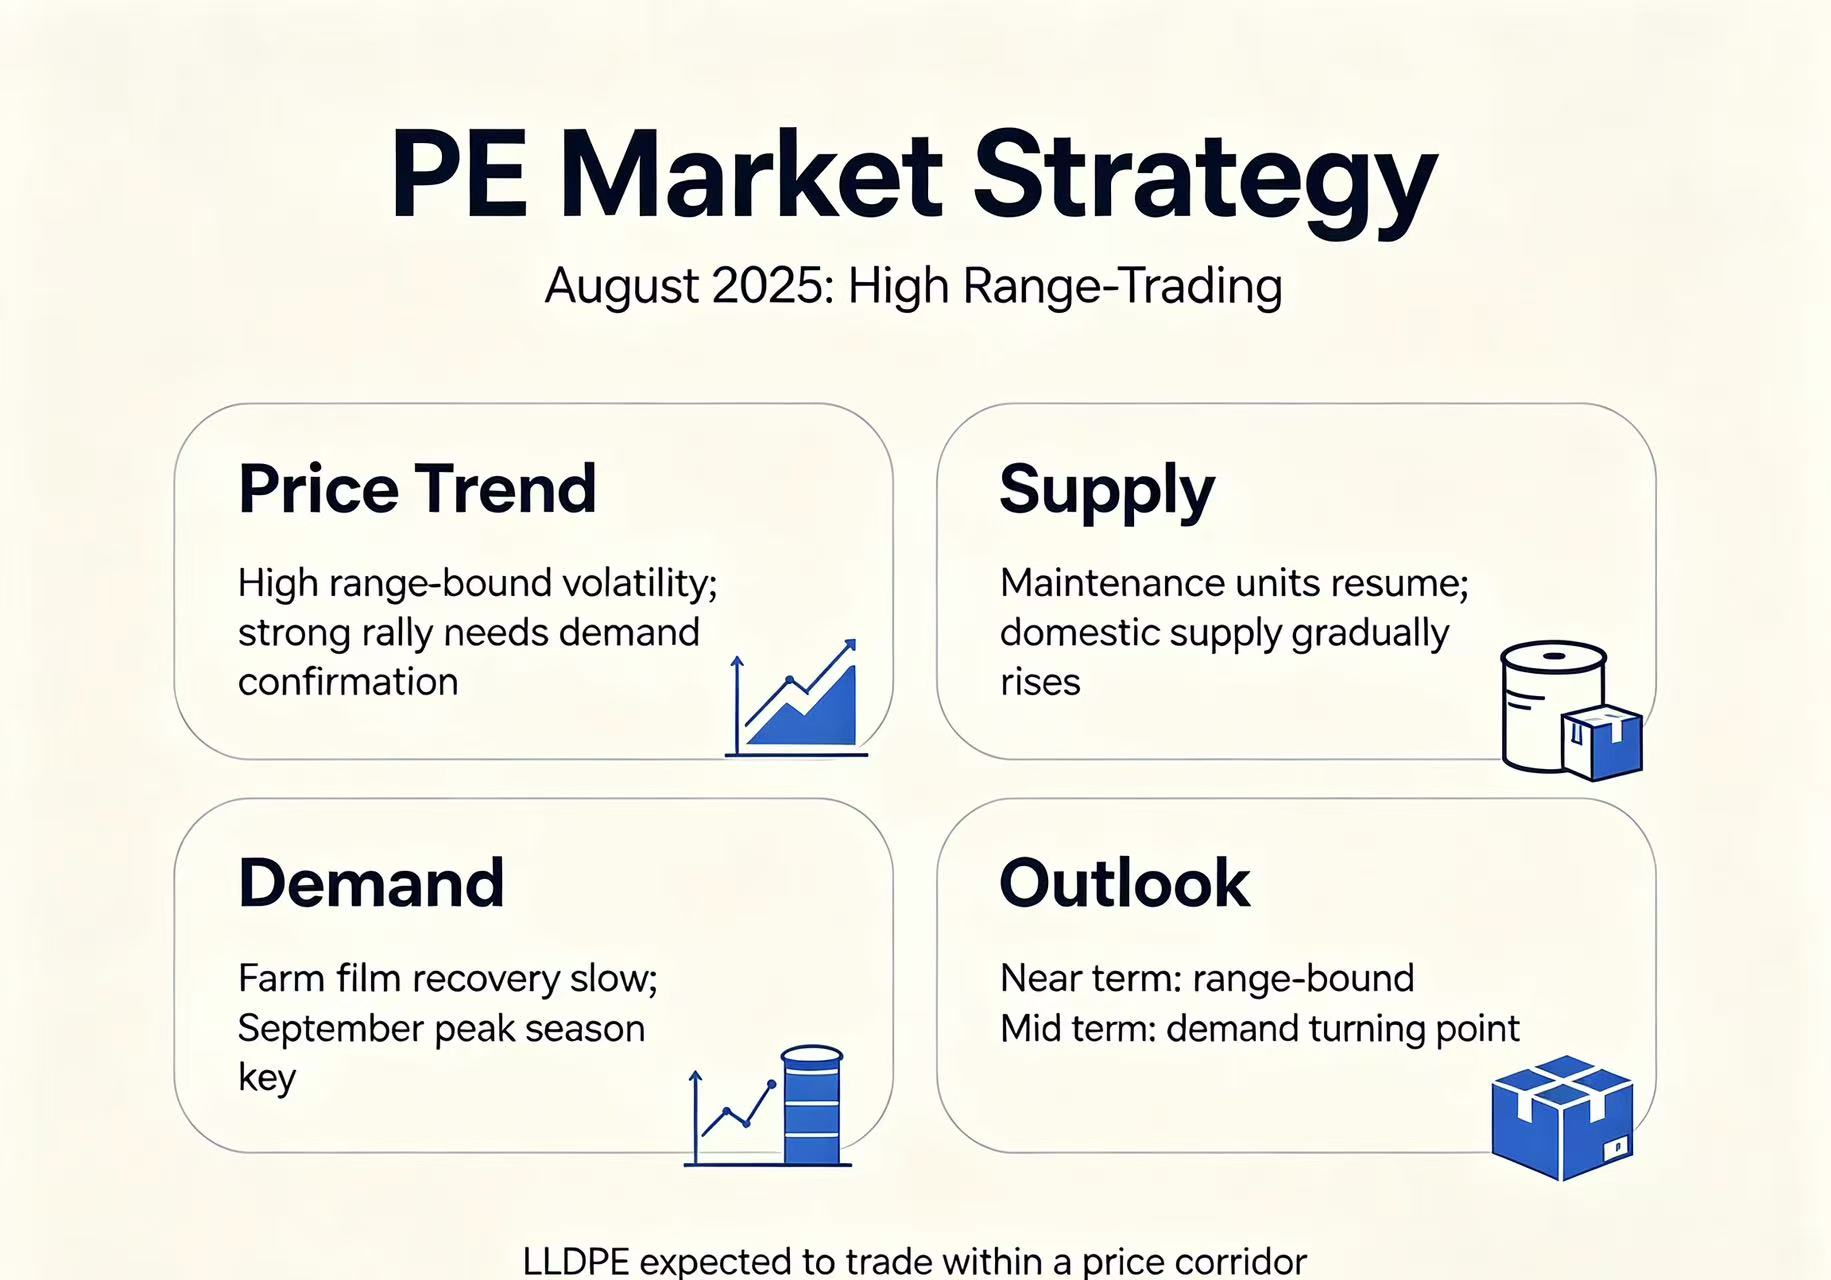
The pull effect of the recent geopolitical conflicts in the Middle East on the market has significantly weakened, the focus of the market has once again shifted to the fundamentals of supply and demand. The current prices of LLDPE is fluctuating within a narrow range of 800-8800 yuan per ton. It is supported by the bottoming out of crude oil costs on the downside, while it is constrained by the fact that the demand for agricultural films is at its lowest point of the year and packaging only meets the basic needs. As of August 12, the average price of LLDPE film was approximately 8230 yuan per ton, rising by around 250 yuan per ton compared to the previous period. However, this increase was mainly driven by costs and sentiment rather than demand. After the trader made the report, the end-users only made small-scale purchases as needed. The actual transaction still required concessions to be made before it could be concluded.
Second: Cost Side: High Volatility in crude Oil, Cost Retains Dominant Pricing weight
International oil prices halted their unilateral surge seen in July during August, with WTI oscillating between 78-82 US dollars per barrel. Shipping volumes through the strait of Hormuz remain subdued, negotiations between the US and Iran remain deadlocked, and geopolitical risk premiums have not fully dissipated. The crude-oil-derived profit margin of LLDPE swings broadly between 80 and 750 yuan/ton, with cost factors still accounting for over 70% of PE pricing drivers. In addition, the weakening RMB exchange rate paired with elevated ocean freight rates continuously compresses profit margins for import cargoes. Middle eastern supply volumes are diverted to European and American markets, resulting in low inbound cargo arrivals in China, which in turn lends certain support to domestic spot prices.

Third: Supply side: Resumption of maintenance turnarounds, Gradual Ramp-up of new capacity
China’s weekly PE output reached approximately 664100 tons with a capacity utilization rate of 78.69%, edging up from the peak maintenance period in July. Few facilities are scheduled for maintenance in August. Overhauled installations in Guangdong Shihua, Yan’an Energy, Yanshan petrochemical and other facilities have resumed operation one after another, driving a gradual rise in overall industry supply. Incremental supply pressure mainly stems from newly commissioned capacity: the full-capacity second-phase 450000 ton/ year plant of Tahe petrochemical started feedstock introduction in July and official production in August, delivering roughly 80000 tons of new monthly supply. Domestic new PE capacity set to launch in the second half of the year totals around 6.3 million tons per annum. Projects including Shandong New times and Zhongsha Gulei are slated to come online between October and November, meaning new supply will be concentrated in the fourth quarter. In the near term, rising supply from domestic cracker lines and plastic producers becomes evident starting late August.

Fourth: Demand side: slow recovery for Agricultural Film, Overall Operating Rates Stay Low
The average operating rate of downstream PE manufacturers registered 35.15% this week, rising 0.48 percentage points week-on-week yet projected to fall by 0.29 percentage points in the coming week. For agricultural film: the overall operating rate has risen 1 percentage point from a week earlier, yet greenhouse film order placement remains sluggish, with a far weaker production rebound compared with previous years. The geomembrane sector is in its off-season, with only a handful of firms lifting operating rates slightly via bidding orders. Greenhouse film producers in some regions have started building order inventories, though production increases fall short of expectations. Still, enterprises have stepped up raw material purchasing, lifting raw material inventory days moderately. In the medium to long run, polyethylene demand is set to pick up between September and October, especially agricultural film consumption, which will see a notable improvement versus the second quarter.
Fifth: Market Outlook: Short-term Range- bound volatility, Mid-term Turning point Determined by supply&Demand
Overall, the PE market will fluctuate at high levels supported by cost bottoms and low inventories in August, yet a sustained strong rally requires matching robust terminal demand. Supply-side maintenance facilities will restart production sequentially to lift domestic supply gradually. On the demand side, agricultural film demand is slowly on a recovery track, while tangible demand improvement awaits the launch of the September peak season. It is expected that LLDPE prices will maintain volatile range trading in the short run. In the medium term, driven by the peak agricultural film season and pre-holiday packaging demand, the market will usher in a demand--driven inflection point.

Your service intention information has been submitted to the platform, we will contact you within 2 working days, please check your email. Thank you.
CPC Index, fully known as China Plastic City Raw Material Price Index, is an important tool to reflect the price trend of plastic raw materials in China Plastic City. The launch of this index aims to provide a reliable reference basis for the majority of plastics industry enterprises to help them better grasp market trends and formulate business strategies.
As the "Industrial Information Operation Situation Index Enterprise" designated by the Ministry of Industry and Information Technology, our company is well aware of the industry's urgent need for accurate and timely plastic price information. Therefore, we officially launched the plastic index in June 2011, providing a professional and authoritative price reference for the majority of plastic enterprises.
The average price is an average price obtained through scientific calculation by our platform according to the price of various plastic products in the whole Chinese market. This average price not only reflects the reference price level of the market as a whole, but also is calculated based on the specific price situation of each sub-brand. In short, the average price is a comprehensive indicator, which reflects the average price level of various plastic products in the Chinese market during a certain period.
By viewing the average price of the market, you can understand the average price trend of various plastic products in a specific period. This helps you to better understand the market dynamics, supply and demand of various products and market competition.
The market reference price refers to the accurate and timely quotation provided by several large traders or agents of a certain brand in China Plastics City. We take the reference price of the brand in Yuyao area on the same day according to the price provided by them. The firm that provides the price is listed as the index gathering firm.
Through the market reference price, you can understand the average price level of the current market, so as to better formulate purchasing, sales and other business strategies. At the same time, the market reference price is also an important basis for users to analyze and forecast the market, helping them grasp the market trend and find business opportunities.
The reference price rise and fall list is a tool to rank the price rise and fall of various categories of plastic products under the market reference price. It tracks and compares the price changes of products under various categories of symbols in different time periods such as week, month and year, and then selects the top 20 with the highest price increase or the top 20 with the highest price decrease to form the price rise list and price fall list respectively.
The reference price rise and fall list provides a practical reference for practitioners in the plastics industry, helping you quickly capture the most volatile products in the market, and providing strong data support for your decision.