Positive factors converge, supporting ABS/PS rebound in August
First. Overall Market Overview
In August 2026, china’s styrene market maintained a firm upward trend amid stability, whit its price center gradually moving higher, driven jointly by crude oil costs and domestic supply-demand dynamics. Multiple positive factors emerged during the month:geopolitical tensions in the Middle East kept fluctuating, continuously lifting upstream costs,multiple domestic production units underwent maintenance and load reduction,resulting in low operating rates and shrinking overall output. Meanwhile, the traditional peak consumption season known as the golden September&Silver October”was approaching, downstream demand slowly rebounded, and port inventories kept declining. Boosted by these multiple favorable factors, styrene prices trended upward, and the fundamental conditions of the industry continued to improve.
Second. Market Price Trend
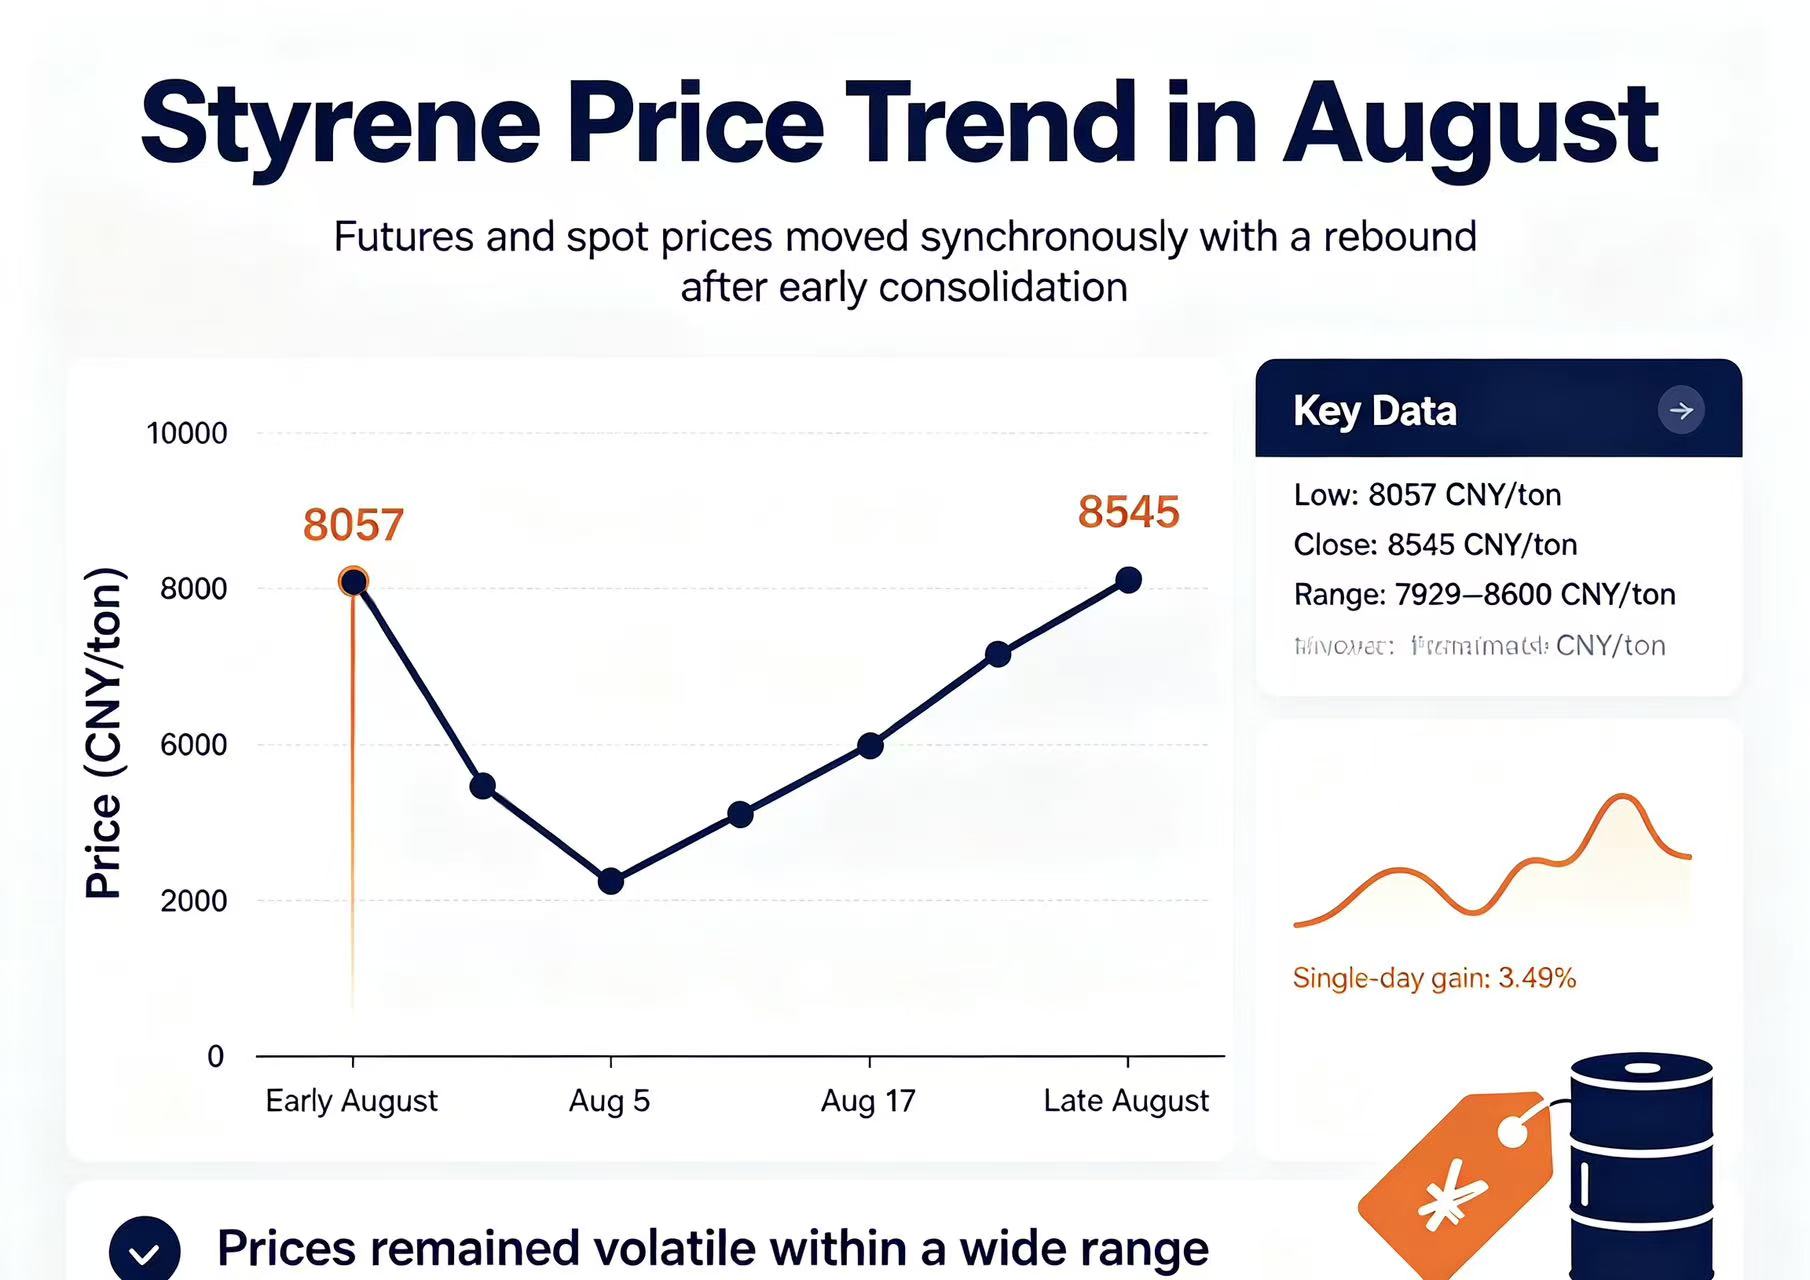
The futures and spot prices of styrene moved in tandem in August, witnessing an initial volatile consolidation followed by a sustained rebound. In the futures market, the main contract trended weakly and fluctuated downward in early August, hitting its monthly low of 8057 yuan per metric ton on August 5, representing a monthly decline of 4.95%. Market sentiment gradually recovered afterwards, and futures prices embarked on a volatile upward trajectory. As of August 17, the closing price of the main contract rebounded to 8545 yuan per metric ton, a single-day gain of 3.49%. Throughout August, styrene prices traded between 7929 yuan and 8600 yuan per metric ton, featuring wide price swings and highly flexible market performance.
 Third. Cost-side conditions
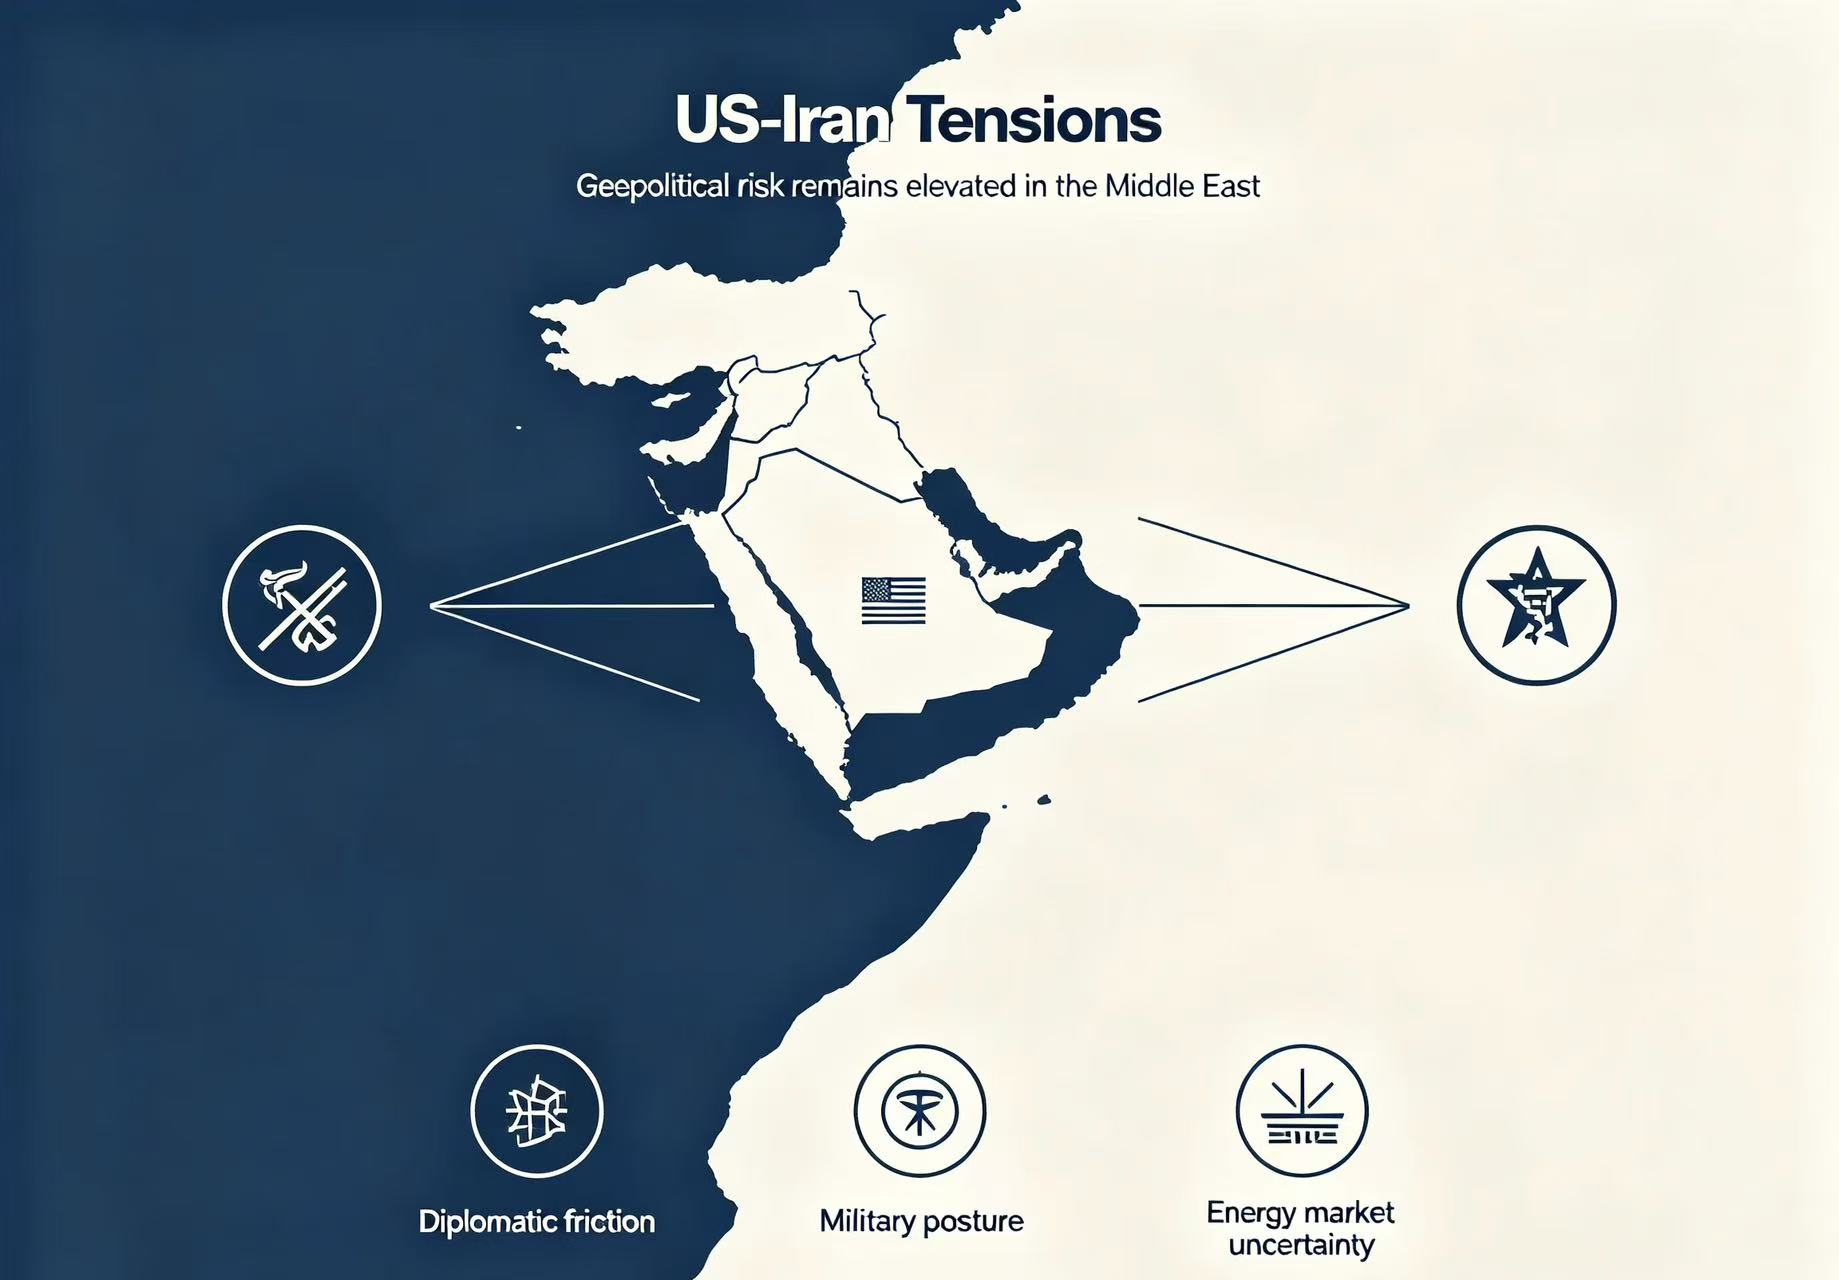
Upward cost support for styrene strengthened consistently in August, primarily fueled by volatile geopolitical developments in the Middle East. Ongoing tensions between the US and Iran restricted shipping traffic in the strait of Hormuz, creating a structural supply deficit in the global crude oil market and keeping international oil prices at elevated volatile levels. As a result, prices of upstream feedstocks including naphtha and pure benzene rose synchronously, lifting the cost benchmark for styrene and laying a solid foundation for the market’s upward movement.
Fourth. Supply side
Domestic styrene supply remained tight in August, with industry operating rates staying low. Affected by concentrated scheduled maintenance and temporary production cuts at existing facilities, domestic styrene output trended downwards. Statistics showed the industry operating rate stood at only 64.85% in July, down 2.60 percentage points from June, and further declined to 62.29%. as of August 13. The supply reduction mainly stemmed from production curbs at major facilities in Quanzhou(East China) and South China regions. Only a small number of Jilin petrochemical plants slightly raised operating rates, resulting in negligible overall output growth that failed to offset the supply shortage.
Fifth . Demand side situation
In August, demand from styrene downstream showed a differentiated trend but overall improved marginally, prompting the market to enter early peak-season procurement mode. The operating rates of the three core downstream products—PS, ABS, and EPS—varied slightly. As of August 13, the average operating rate across the three main styrene downstream sectors was approximately 51.90%, indicating stable overall operations. Among them, ABS operating rates rose to around 60.7%; PS operating rates steadily increased to about 45%; while EPS operating rates saw a slight decline to approximately 50%.
Sixth. Inventory status
Low inventory levels were one of the key positive factors in the styrene market in August, with domestic port inventories continuing to decline steadily. Previously, East China port inventories had already dropped significantly from their high levels in March. As of August 10, Jiangsu's styrene port inventory stood at 84,800 tons, down by another 18,000 tons week-on-week. Meanwhile, port withdrawal activity remained stable, with weekly withdrawals reaching 33,300 tons. Industry insiders expect that arrivals of styrene at major domestic ports in August will remain limited, and the tight supply situation is likely to persist. Inventories are expected to continue falling to low levels, further tightening the overall supply-demand balance and providing strong support for market prices.
Seventh. Import and Export Situation
Since the beginning of this year, domestic styrene imports have sharply declined, with cumulative imports from January to June dropping by 83.83% year-on-year. In August, import supplies remained extremely scarce, and domestic market supply was almost entirely supported by local production capacity. On the export side, favorable conditions emerged: due to global geopolitical tensions, overseas supply became tight, significantly enhancing China's export competitiveness. Export volumes in August rose noticeably compared to the previous month, effectively absorbing excess domestic supply and further supporting inventory reduction. From a supply-demand perspective, total styrene supply contracted while demand increased in August, shifting the market balance from loose to tight and entering an overall state of structural supply shortage.
Eighth. Market Outlook
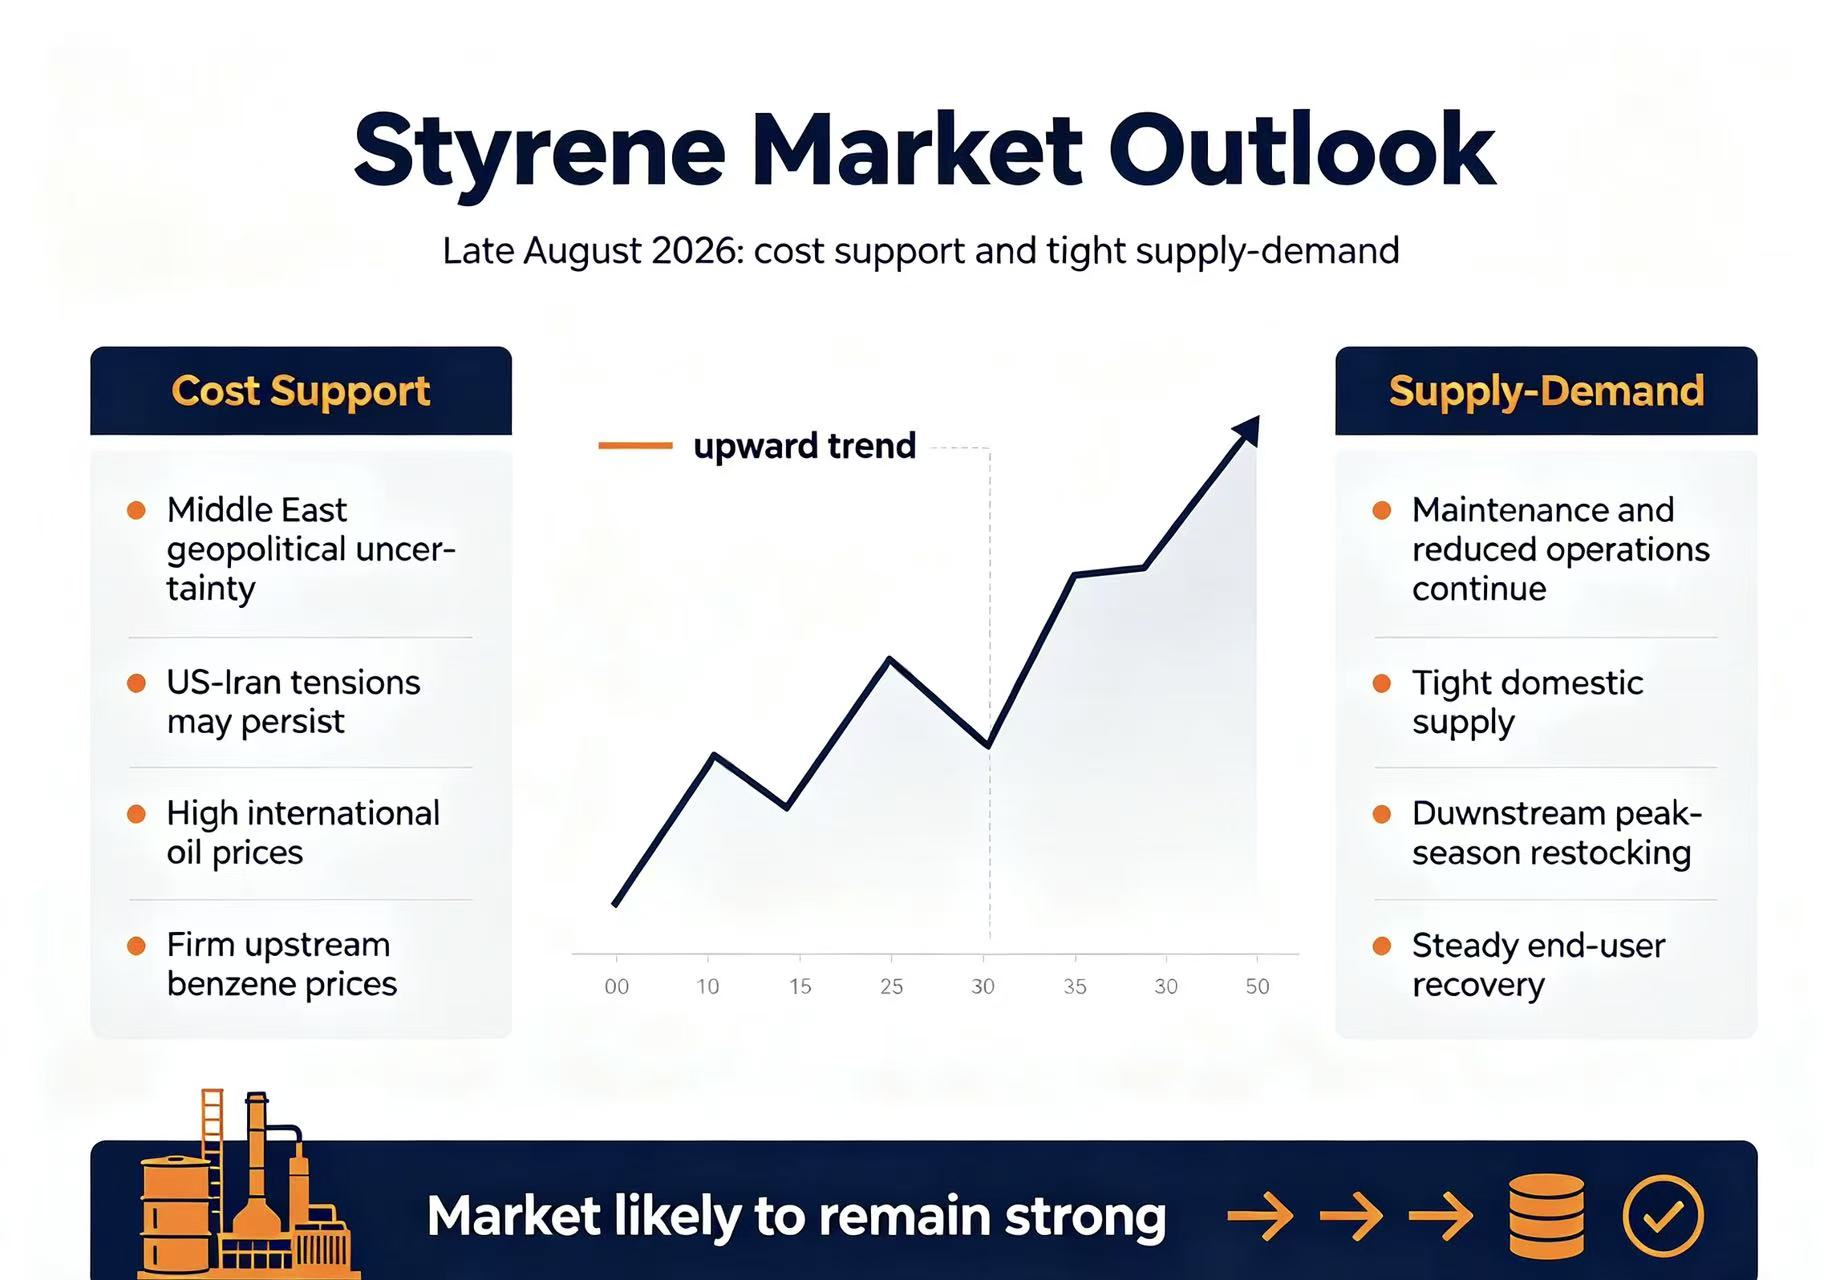
Overall, china’s styrene market in late August 2026 will continue to follow the core logic of cost support plus tight supply and demand, maintaining an overall volatile upward trend. On the cost side, geopolitical uncertainties linger in the Middle East, US-Iran tensions cannot be eased in the short term, so high international crude oil price support will stay intact. Prices of upstream feedstocks such as pure benzene will remain firm to sustain lasting positive cost driver. On the supply and demand side, maintenance and load reduction at domestic styrene plants will continue in the near term to keep market supply tight. Meanwhile, downstream pre-season stocking demand will heat up alongside steady recovery in end-user consumption, which will further widen the supply-demand gap. Coupled with market sentiment driven by low port inventories, the styrene market is highly likely to stay strong in tyhe follow-up period.

Your service intention information has been submitted to the platform, we will contact you within 2 working days, please check your email. Thank you.
CPC Index, fully known as China Plastic City Raw Material Price Index, is an important tool to reflect the price trend of plastic raw materials in China Plastic City. The launch of this index aims to provide a reliable reference basis for the majority of plastics industry enterprises to help them better grasp market trends and formulate business strategies.
As the "Industrial Information Operation Situation Index Enterprise" designated by the Ministry of Industry and Information Technology, our company is well aware of the industry's urgent need for accurate and timely plastic price information. Therefore, we officially launched the plastic index in June 2011, providing a professional and authoritative price reference for the majority of plastic enterprises.
The average price is an average price obtained through scientific calculation by our platform according to the price of various plastic products in the whole Chinese market. This average price not only reflects the reference price level of the market as a whole, but also is calculated based on the specific price situation of each sub-brand. In short, the average price is a comprehensive indicator, which reflects the average price level of various plastic products in the Chinese market during a certain period.
By viewing the average price of the market, you can understand the average price trend of various plastic products in a specific period. This helps you to better understand the market dynamics, supply and demand of various products and market competition.
The market reference price refers to the accurate and timely quotation provided by several large traders or agents of a certain brand in China Plastics City. We take the reference price of the brand in Yuyao area on the same day according to the price provided by them. The firm that provides the price is listed as the index gathering firm.
Through the market reference price, you can understand the average price level of the current market, so as to better formulate purchasing, sales and other business strategies. At the same time, the market reference price is also an important basis for users to analyze and forecast the market, helping them grasp the market trend and find business opportunities.
The reference price rise and fall list is a tool to rank the price rise and fall of various categories of plastic products under the market reference price. It tracks and compares the price changes of products under various categories of symbols in different time periods such as week, month and year, and then selects the top 20 with the highest price increase or the top 20 with the highest price decrease to form the price rise list and price fall list respectively.
The reference price rise and fall list provides a practical reference for practitioners in the plastics industry, helping you quickly capture the most volatile products in the market, and providing strong data support for your decision.