PC: After lying in wait, now poised to strike!
After a weak consolidation and brief period of stagnation in July, the PC market experienced a phased rebound in August, with spot prices rising steadily and factory ex-factory prices gradually increasing. The industry has fully moved past the sluggish and volatile conditions of July, forming a multi-factor upward trend driven by cost support, tight supply, recovering demand, and bullish market sentiment.
Raw material costs rebound, strengthening the price floor.
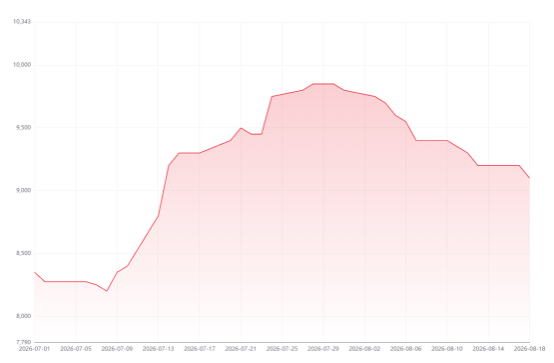
Figure 1: price trend of bisphenol A in East china from july to present
The core raw materials for PC—bisphenol A, pure benzene, acetone, and phenol—remained firm and generally trending upward in August. Combined with relatively strong international crude oil prices and fluctuating operating loads at some overseas petrochemical plants, supply from upstream basic materials tightened, driving continuous price increases. In contrast to July, when weak raw material prices dragged down the market, August saw a complete reversal of this downward trend, providing solid bottom support for the PC market. As upstream costs steadily rose, they effectively compressed production margins for PC manufacturers, prompting factories to collectively adjust prices to pass on higher costs, thus laying a solid foundation for finished product price increases. The price transmission along the industrial chain remained smooth and efficient.
Supply contraction and improved supply-demand dynamics
Since August, several major domestic PC production facilities have continued operating at reduced capacity or undergoing maintenance, keeping the overall industry utilization rate at a relatively low to moderate level. Leading companies such as Wanhua Chemical and Hengli Petrochemical have implemented supply controls based on demand, moderately restricting output and directly tightening the domestic supply flow. Meanwhile, the PC industry is currently in a period of no new capacity additions, allowing the earlier surge in supply to be fully absorbed, marking a definitive departure from the oversupplied, loose market conditions seen in July. On the import front, fluctuations in overseas plant operations and international logistics have led to a month-on-month decline in imported arrivals in August, further helping to fill the domestic supply gap. The combination of short-term supply contraction and low inventory levels has shifted the PC market in August from a state of loose supply-demand balance to a tight equilibrium, creating the core conditions for sustained price increases.
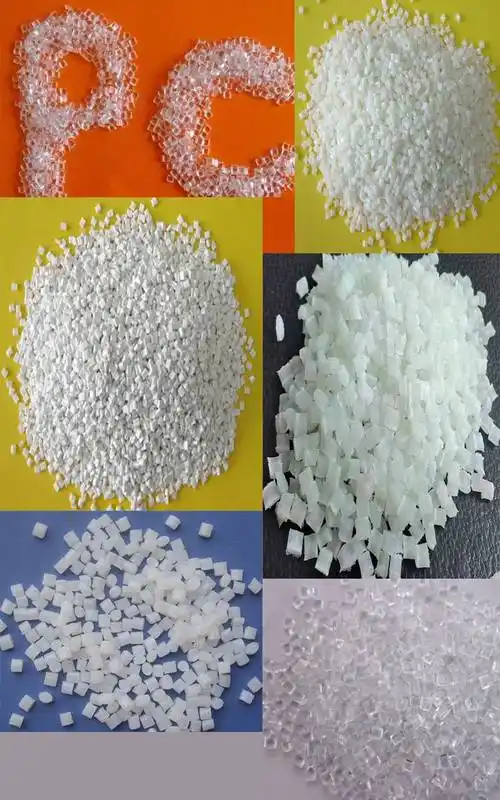
Downstream demand is recovering, and the capacity to support essential needs has strengthened.
Under the traditional "golden September, silver October" peak season expectations, downstream industries such as automotive, electronics, and photovoltaic building materials have begun replenishing inventory in advance. Demand in the automotive lightweighting sector remains steadily released, with orders for PC components used in new energy vehicle exteriors, headlights, and charging stations increasing steadily. The electronics and home appliances sectors are concluding their off-season period, seeing a recovery in orders that has boosted procurement of general-purpose PC materials. Additionally, demand in August remained stable in areas such as photovoltaic daylighting panels and outdoor construction materials, prompting end-user companies to capitalize on the low-price window from July to August by concentrating on inventory restocking, significantly enhancing market demand resilience.
Market sentiment is improving, and industry confidence is recovering.
As fundamentals continued to improve in August, market pessimism completely dissipated. Traders, having depleted their low-level inventories, showed strong reluctance to sell and a firm intent to support prices. End users anticipated sustained price increases, leading to more forward booking and early stockpiling, which further boosted trading activity and amplified both the magnitude of price hikes and the durability of the upward trend.
In summary, this round of price increases represents a return to value following short-term industry adjustments. Inventory reduction in July and capacity clearance laid the foundation for market recovery, while favorable factors—including costs, supply, demand, and sentiment—converged in August, driving the sector's gradual rebound. In the short term, prices remain firm at higher levels; in the medium to long term, as peak-season demand materializes, industry sentiment will continue to improve, potentially ushering in a phase of steady, sustained upward momentum.

Your service intention information has been submitted to the platform, we will contact you within 2 working days, please check your email. Thank you.
CPC Index, fully known as China Plastic City Raw Material Price Index, is an important tool to reflect the price trend of plastic raw materials in China Plastic City. The launch of this index aims to provide a reliable reference basis for the majority of plastics industry enterprises to help them better grasp market trends and formulate business strategies.
As the "Industrial Information Operation Situation Index Enterprise" designated by the Ministry of Industry and Information Technology, our company is well aware of the industry's urgent need for accurate and timely plastic price information. Therefore, we officially launched the plastic index in June 2011, providing a professional and authoritative price reference for the majority of plastic enterprises.
The average price is an average price obtained through scientific calculation by our platform according to the price of various plastic products in the whole Chinese market. This average price not only reflects the reference price level of the market as a whole, but also is calculated based on the specific price situation of each sub-brand. In short, the average price is a comprehensive indicator, which reflects the average price level of various plastic products in the Chinese market during a certain period.
By viewing the average price of the market, you can understand the average price trend of various plastic products in a specific period. This helps you to better understand the market dynamics, supply and demand of various products and market competition.
The market reference price refers to the accurate and timely quotation provided by several large traders or agents of a certain brand in China Plastics City. We take the reference price of the brand in Yuyao area on the same day according to the price provided by them. The firm that provides the price is listed as the index gathering firm.
Through the market reference price, you can understand the average price level of the current market, so as to better formulate purchasing, sales and other business strategies. At the same time, the market reference price is also an important basis for users to analyze and forecast the market, helping them grasp the market trend and find business opportunities.
The reference price rise and fall list is a tool to rank the price rise and fall of various categories of plastic products under the market reference price. It tracks and compares the price changes of products under various categories of symbols in different time periods such as week, month and year, and then selects the top 20 with the highest price increase or the top 20 with the highest price decrease to form the price rise list and price fall list respectively.
The reference price rise and fall list provides a practical reference for practitioners in the plastics industry, helping you quickly capture the most volatile products in the market, and providing strong data support for your decision.