Can the upward trend of PE continue before the peak season?
[Introduction] In August, the PE market continued to shift upward in price, supported by high maintenance shutdowns and low inventory levels. Expectations for the traditional peak season—“golden September and silver October”—further boosted market sentiment. However, end users' resistance to higher-priced supplies has been growing steadily, and actual trading activity remains weak. With costs and demand pulling in opposite directions, it remains uncertain whether the upward trend in PE prices can continue smoothly.
First: Supply remains tight, with short-term pressures yet to emerge.
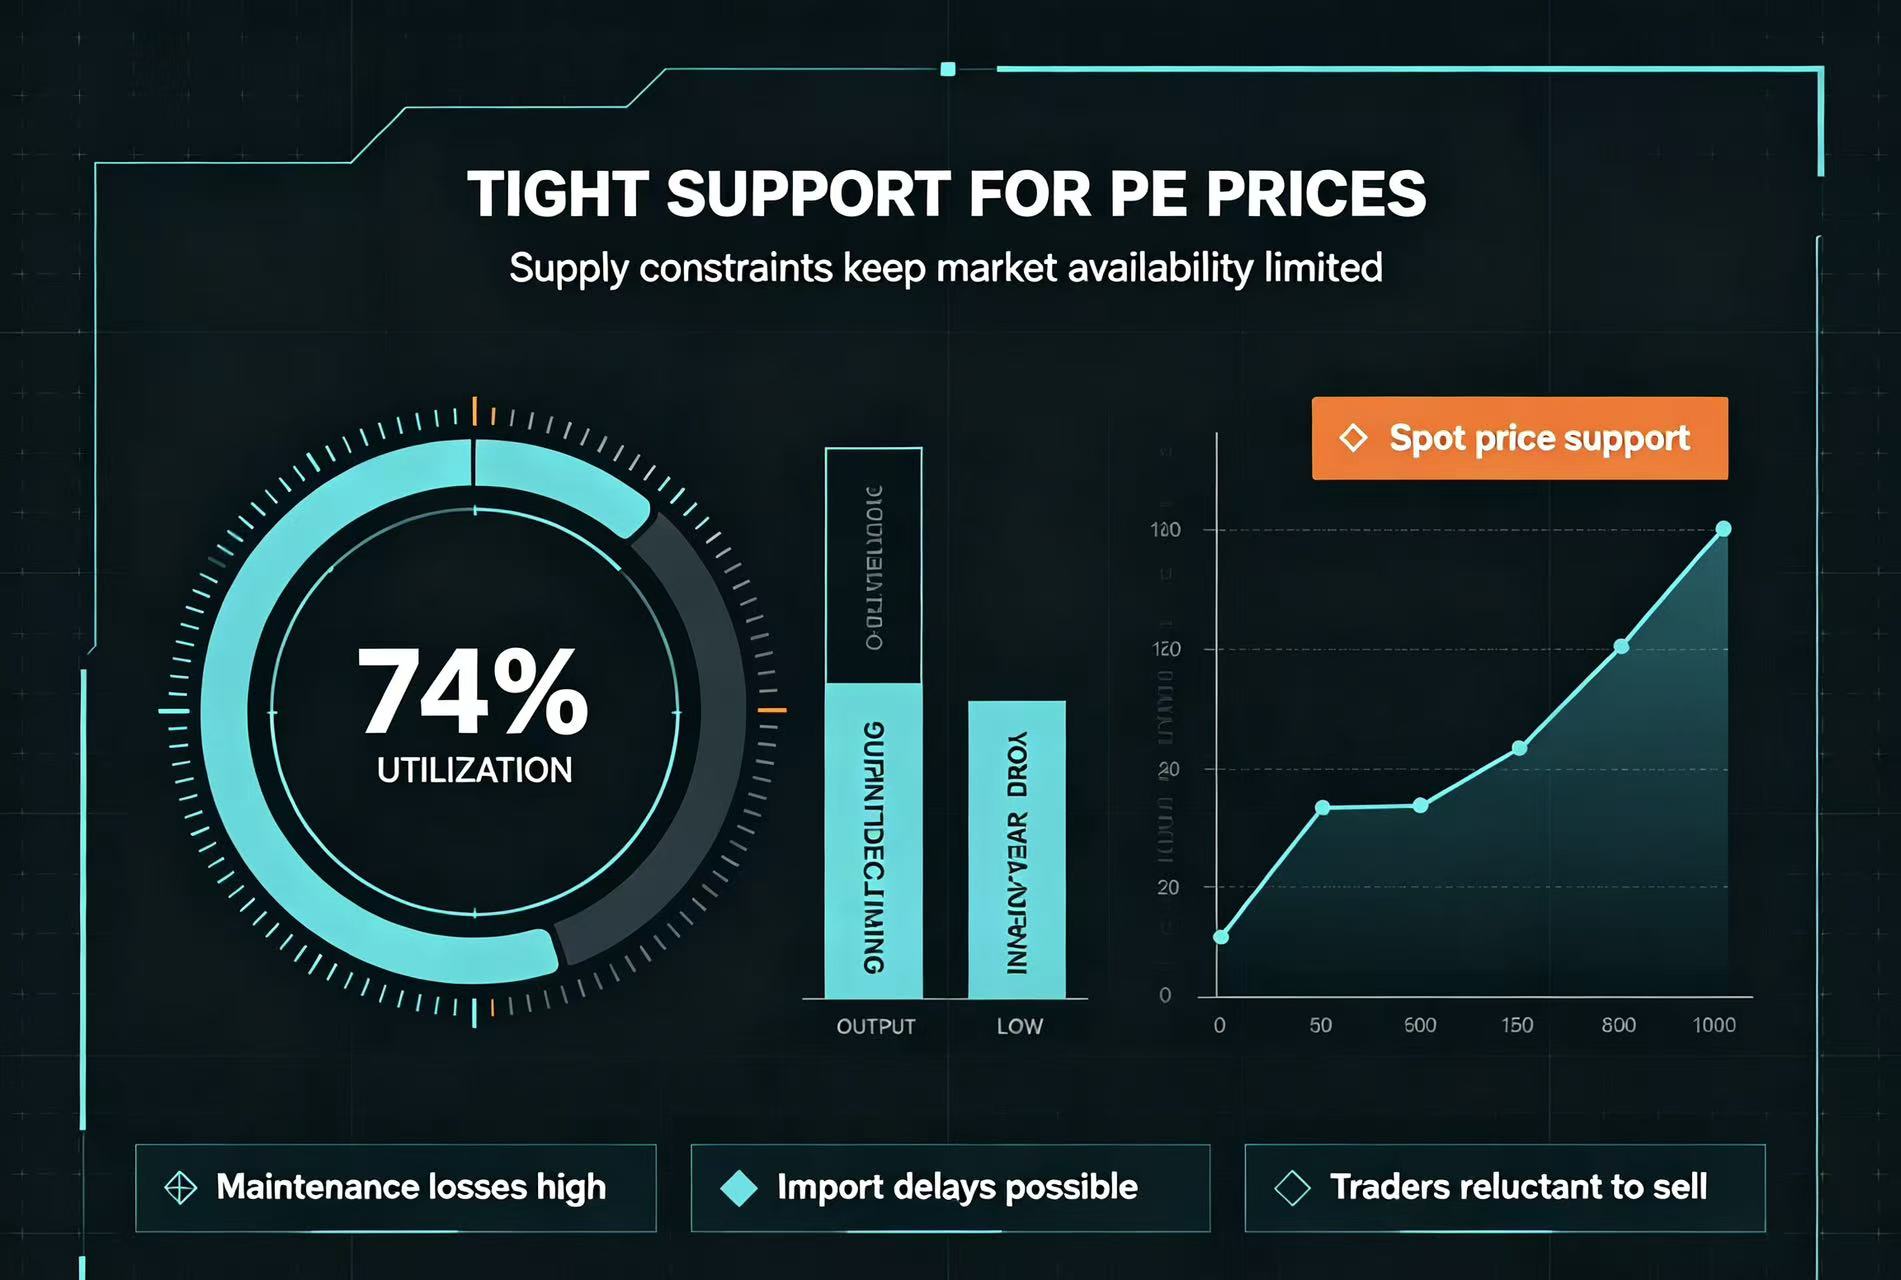
Recently, domestic PE plant maintenance losses have remained high, and combined with potential delays in the arrival of some imported supplies, overall market availability has tightened, providing strong support for spot prices. Currently, upstream producers' capacity utilization is hovering around 74%, with monthly output declining compared to the previous month, while social inventory levels remain at a low point relative to the same period over the past two years. Although inventory at certain warehouses has seen slight accumulation, year-on Year declines remain significant. Traders have limited available stock, leading to growing reluctance to sell.
Second: Demand is gradually recovering, and expectations for the peak season are slowly warming up.
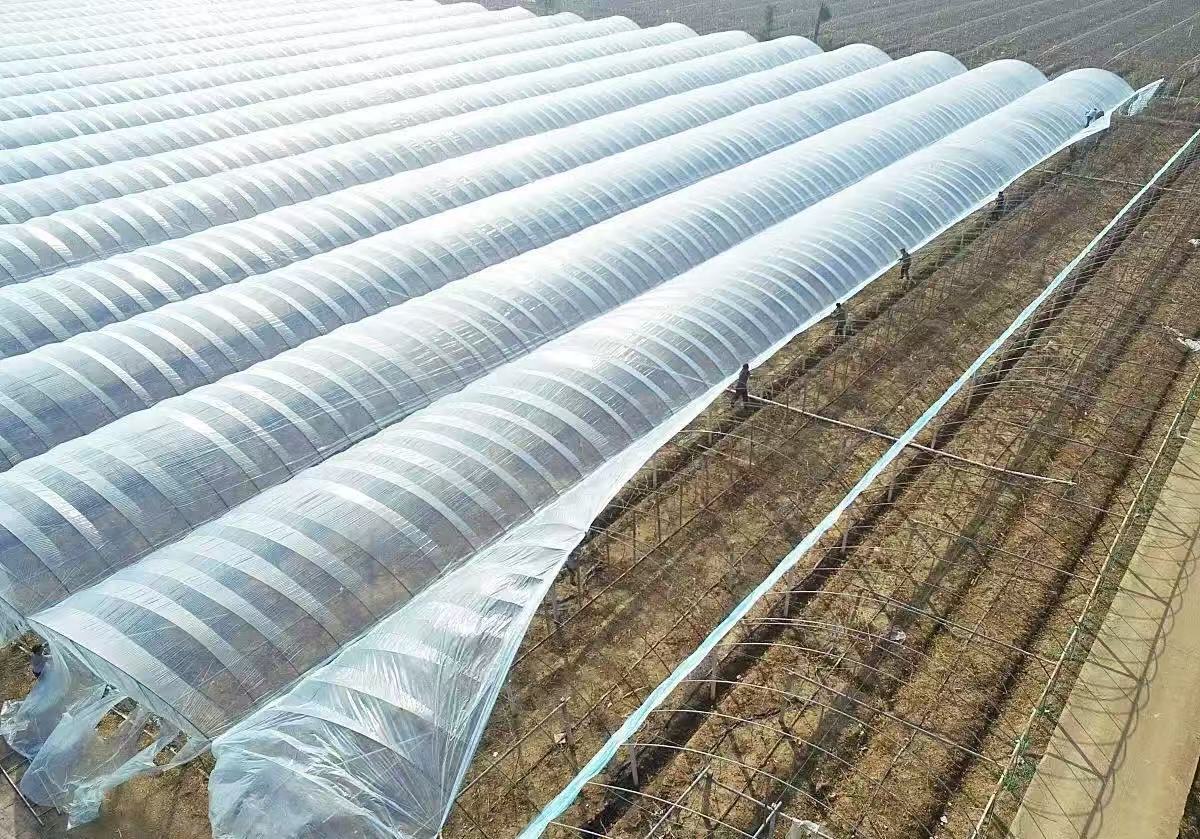
Currently, overall downstream operating rates have slightly increased compared to earlier periods, with the agricultural film sector showing a notable rebound. Orders for greenhouse films in northern regions are starting to pick up, and the market is gradually entering the traditional production peak season's inventory preparation phase. The packaging film industry has also seen moderate improvement in operations, as the approaching e-commerce peak season brings some optimism about renewed demand for films. However, the market remains in a transitional period between low and high seasons. Industries such as packaging, injection molding, and pipe materials continue to face slow recovery due to high temperatures, while profit margins for product manufacturers remain compressed by rising raw material prices. As a result, most companies are maintaining a just-in-time procurement approach, with limited willingness to chase price increases.

Third. Cost and Sentiment Resonance Drive Price Center Higher
International crude oil prices have remained high, providing solid cost support to the PE market. With tight supply, low inventory levels, and seasonal demand expectations converging, traders have generally maintained firm pricing attitudes. Factory gate prices have continued to rise, pushing the overall price center upward. Although end users remain hesitant toward higher-priced materials, low-cost resources are becoming increasingly scarce. Coupled with rising factory prices, traders have limited room for concessions, resulting in a market characterized by ease of upward movement and resistance to downward adjustments.
Fourth. Outlook: High-end consolidation, with potential for further upward shift in price
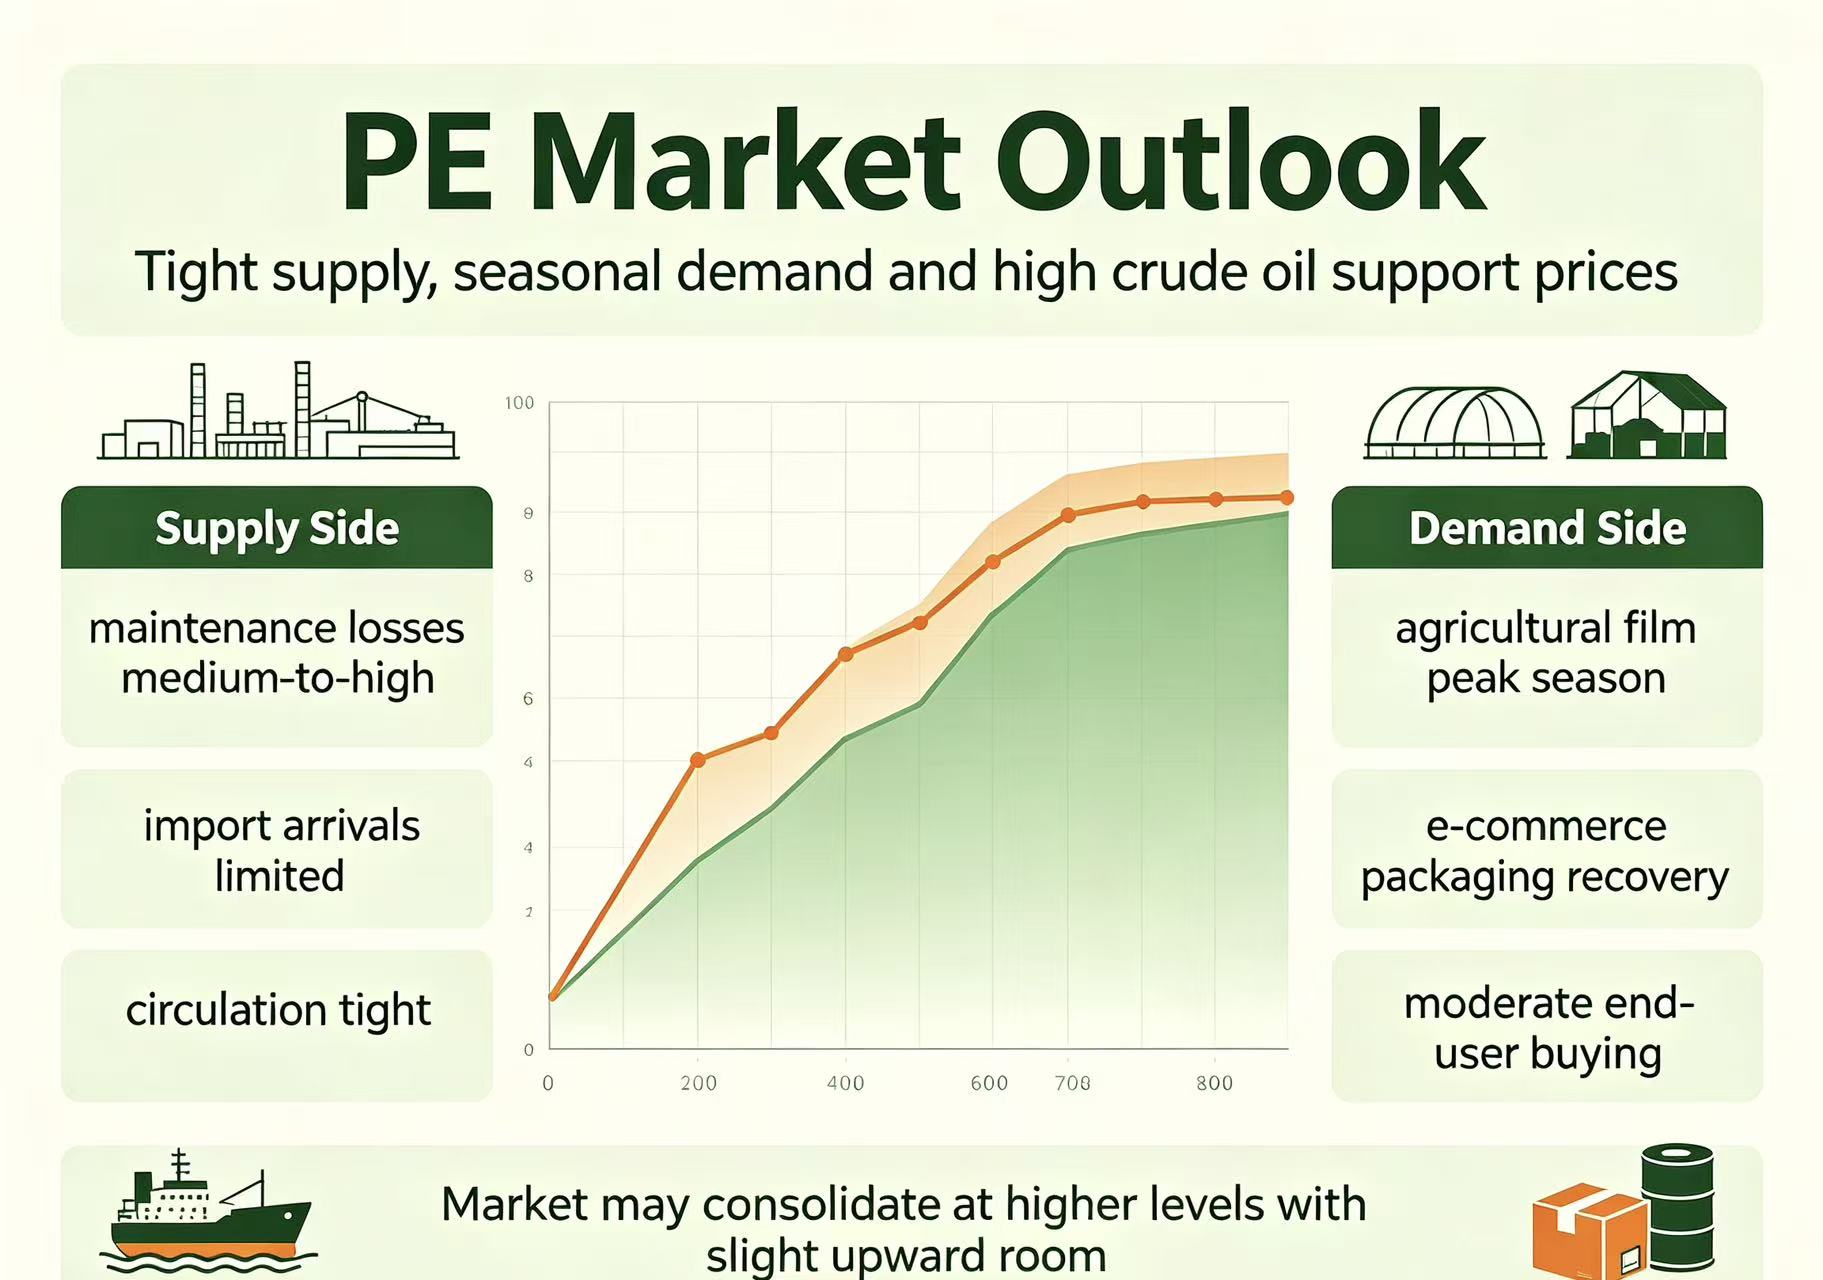
Overall, supply-side maintenance losses are expected to remain at a medium-to-high level in the short term, while limited import arrivals will offer only modest replenishment, keeping market circulation tight and unlikely to improve significantly. On the demand side, as the peak season for agricultural films progresses and e-commerce packaging demand recovers, end-user purchases are likely to increase moderately. With marginal improvements in both supply and demand, coupled with sustained high crude oil prices, PE prices are well supported from below. However, recent rapid price increases have led to growing resistance among end users, slowing down actual transaction volumes. In the near term, the market is likely to consolidate at higher levels, with room for a slight upward adjustment in price.

Your service intention information has been submitted to the platform, we will contact you within 2 working days, please check your email. Thank you.
CPC Index, fully known as China Plastic City Raw Material Price Index, is an important tool to reflect the price trend of plastic raw materials in China Plastic City. The launch of this index aims to provide a reliable reference basis for the majority of plastics industry enterprises to help them better grasp market trends and formulate business strategies.
As the "Industrial Information Operation Situation Index Enterprise" designated by the Ministry of Industry and Information Technology, our company is well aware of the industry's urgent need for accurate and timely plastic price information. Therefore, we officially launched the plastic index in June 2011, providing a professional and authoritative price reference for the majority of plastic enterprises.
The average price is an average price obtained through scientific calculation by our platform according to the price of various plastic products in the whole Chinese market. This average price not only reflects the reference price level of the market as a whole, but also is calculated based on the specific price situation of each sub-brand. In short, the average price is a comprehensive indicator, which reflects the average price level of various plastic products in the Chinese market during a certain period.
By viewing the average price of the market, you can understand the average price trend of various plastic products in a specific period. This helps you to better understand the market dynamics, supply and demand of various products and market competition.
The market reference price refers to the accurate and timely quotation provided by several large traders or agents of a certain brand in China Plastics City. We take the reference price of the brand in Yuyao area on the same day according to the price provided by them. The firm that provides the price is listed as the index gathering firm.
Through the market reference price, you can understand the average price level of the current market, so as to better formulate purchasing, sales and other business strategies. At the same time, the market reference price is also an important basis for users to analyze and forecast the market, helping them grasp the market trend and find business opportunities.
The reference price rise and fall list is a tool to rank the price rise and fall of various categories of plastic products under the market reference price. It tracks and compares the price changes of products under various categories of symbols in different time periods such as week, month and year, and then selects the top 20 with the highest price increase or the top 20 with the highest price decrease to form the price rise list and price fall list respectively.
The reference price rise and fall list provides a practical reference for practitioners in the plastics industry, helping you quickly capture the most volatile products in the market, and providing strong data support for your decision.