Shock! PVC imports and exports both decline, hitting the lowest level of the year
The first rising then declining “ trend of the PVC market in 2026 fully materialized in July, with both import and export trade weakening simultaneously. Import and export figures both dropped sharply, hitting their lowest monthly levels so far this year. The earlier pattern-strong exports in the first quarter and continuous contraction in imports-has been completely reversed. A combination of weak overseas demand during the off-season, rising domestic self-sufficiently rates,and volatile global trade conditions has brought about a turning point in the PVC industry’s import-export dynamics, sending clear signals regarding supply and demand trends for the second half of the year.
Export volumes sharply declined due to the overseas off-season and weak demand.
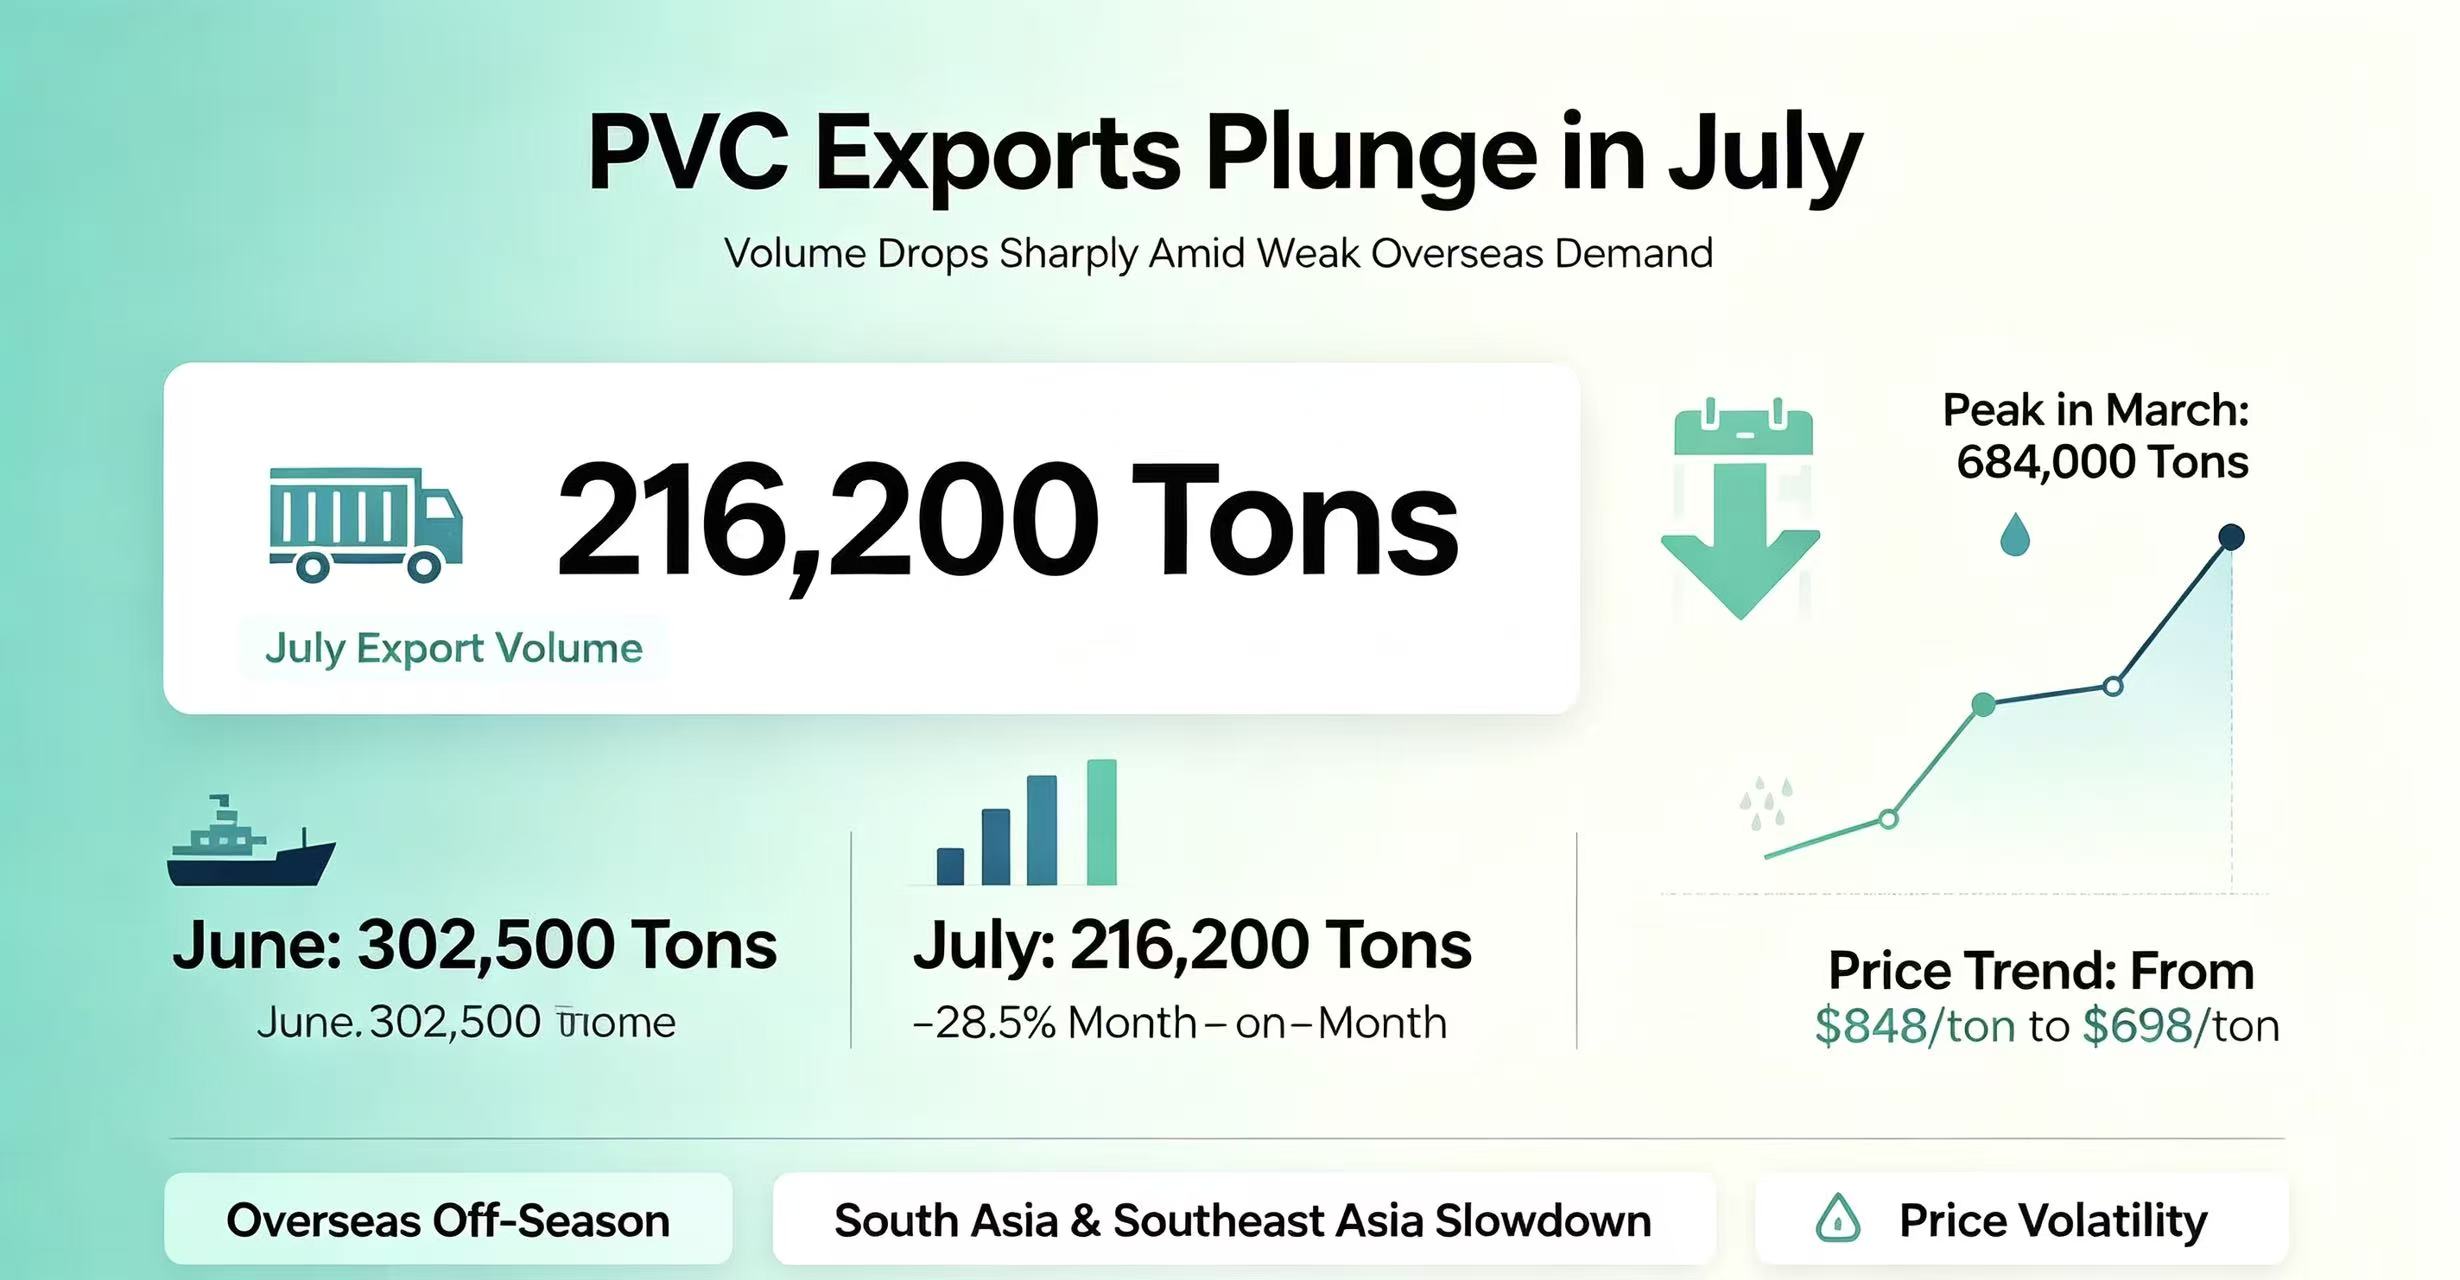
According to custom data, PVC exports in July this year amounted to only 216,200 tons, a sharp 28.5% decline from June’s 302,500 tons, plunging to the lowest monthly export level of the year and nearly having compared to March’ s annual peak of 684,000 tons. The primary reason lies in overseas mainstream markets entering their traditional off-season, with regional demand weakening significantly. As widely known, PVC exports are highly dependent on south Asia and Southeast Asia, with India, Vietnam, and Indonesia-the three core markets-accounting for over 50% of total exports. This high market concentration makes export Trends extremely vulnerable to regional dynamics. India, the largest export destination, has seen a steep drop in demand, importing just 34,500 tons of PVC from China in July, down 88.2% from the peak of 293,000 tons in march, and experiencing consecutive months of decline. Meanwhile, Southeast Asia entered its rainy season in July, causing construction activities in infrastructure, pipes, and profiles to halt, leading to reduced imports in Vietnam and Indonesia and a rapid fade in regional export advantages. At the same time, fluctuating export prices have eroded product competitiveness, further suppressing overseas orders. After reaching an annual high of $848 per ton in April 2026, the average export price continued to decline, dropping to $698 per ton in July. Amid volatile pricing, overseas buyers have adopted a cautious stance, showing low willingness to commit to long-term contracts and limiting purchases to short-term essential needs, directly resulting in a significant contraction in monthly export volumes.
Domestic capacity is sufficient, and with import substitution taking effect, PVC imports continue to hit bottom.
Compared to the temporary decline in exports, the weak performance of PVC imports has been the core trend throughout 2026, with July's new low merely reflecting the continuation of the industry's long-term structural shift. In recent years, China's domestic PVC industry has continuously optimized its capacity structure, with new capacity additions shrinking and supply rhythms stabilizing. Meanwhile, both calcium carbide-based and ethylene-based production technologies have matured, leading to steady improvements in product quality that fully meet domestic downstream demand. Under these conditions, China's PVC self-sufficiency rate has steadily increased, and the arbitrage window for imports has remained closed over the long term. On one hand, domestic spot prices have consistently remained below international market levels, leaving no profit margin for overseas suppliers entering the Chinese market, effectively halting general trade imports. On the other hand, downstream processing enterprises increasingly prefer domestically produced supplies offering better cost-performance ratios, with only minimal import volumes maintained through processing trade to meet essential needs. Driven by multiple factors, PVC import volumes have continued to fall sharply year-on-year since 2026, with cumulative imports from January to June down nearly 40% compared to the same period last year. The downward trend continued into July, setting a new annual low, firmly solidifying the trajectory toward import substitution.
In summary, the low levels of PVC imports and exports in July were not coincidental, but rather a reflection of overseas off-season demand, relaxed domestic supply-demand conditions, and weak global trade. In the short term, overseas market demand is unlikely to recover quickly in August and September, as the monsoon seasons in South Asia and Southeast Asia continue to impact activity. Exports are expected to to remain at low levels, while imports will likely maintain their downward trend, supported by ample domestic production capacity, with little chance of a significant rebound.

Your service intention information has been submitted to the platform, we will contact you within 2 working days, please check your email. Thank you.
CPC Index, fully known as China Plastic City Raw Material Price Index, is an important tool to reflect the price trend of plastic raw materials in China Plastic City. The launch of this index aims to provide a reliable reference basis for the majority of plastics industry enterprises to help them better grasp market trends and formulate business strategies.
As the "Industrial Information Operation Situation Index Enterprise" designated by the Ministry of Industry and Information Technology, our company is well aware of the industry's urgent need for accurate and timely plastic price information. Therefore, we officially launched the plastic index in June 2011, providing a professional and authoritative price reference for the majority of plastic enterprises.
The average price is an average price obtained through scientific calculation by our platform according to the price of various plastic products in the whole Chinese market. This average price not only reflects the reference price level of the market as a whole, but also is calculated based on the specific price situation of each sub-brand. In short, the average price is a comprehensive indicator, which reflects the average price level of various plastic products in the Chinese market during a certain period.
By viewing the average price of the market, you can understand the average price trend of various plastic products in a specific period. This helps you to better understand the market dynamics, supply and demand of various products and market competition.
The market reference price refers to the accurate and timely quotation provided by several large traders or agents of a certain brand in China Plastics City. We take the reference price of the brand in Yuyao area on the same day according to the price provided by them. The firm that provides the price is listed as the index gathering firm.
Through the market reference price, you can understand the average price level of the current market, so as to better formulate purchasing, sales and other business strategies. At the same time, the market reference price is also an important basis for users to analyze and forecast the market, helping them grasp the market trend and find business opportunities.
The reference price rise and fall list is a tool to rank the price rise and fall of various categories of plastic products under the market reference price. It tracks and compares the price changes of products under various categories of symbols in different time periods such as week, month and year, and then selects the top 20 with the highest price increase or the top 20 with the highest price decrease to form the price rise list and price fall list respectively.
The reference price rise and fall list provides a practical reference for practitioners in the plastics industry, helping you quickly capture the most volatile products in the market, and providing strong data support for your decision.