Import and export trends from January to July: PS reverses, ABS holds steady
From January to July 2026, the domestic import and export markets for ABS and PS, two major general-purpose plastics, showed significant divergence and structural reshaping. The PS plastic market underwent a fundamental shift in its trade pattern, with imports continuously declining and exports surging sharply, officially entering a net-export phase. In contrast, the ABS plastic market maintained its traditional import-dominated structure; however, as new domestic ABS capacity continued to come online and self-sufficiency rates steadily rose, the industry's reliance on imports slightly decreased, enabling modest growth in exports. Nevertheless, strong demand for high-end grades still necessitates continued imports.
First. Import and Export Operations of PE plastic
From January to July 2026, China’s PS plastic trade showed a divergent trend, with imports continuing to contract at low levels while export surged, marking a complete shift in trade status from traditional net imports to regular net exports- the most significant structural change in the PS plastic sector this year. On the import side, from January to July, China's cumulative PS imports reached 226,400 tons, down 27,500 tons year-on-year—a decline of 10.83%, marking a continued record low in recent years. Monthly trends showed slight fluctuations, with imports in July alone totaling 28,800 tons, down 5,100 tons month-on-month and 10,100 tons year-on-year, indicating persistently weak import demand. The core reason for the shrinking imports lies in the continuous release of domestic production capacity, significantly boosting self-sufficiency rates for general-purpose PS. Domestic products have now achieved strong international competitiveness in both quality and cost, deepening the import substitution effect. Meanwhile, domestic PS spot prices have remained at long-term global lows, narrowing arbitrage opportunities for imports and dampening traders' willingness to import. This has been further compounded by Middle East geopolitical conflicts restricting supply from traditional importing countries such as Iran and Saudi Arabia, further compressing import volumes.
In terms of exports, from January to July, China’s cumulative PS export volume reached 276,900 tons, an increases of 95,100 tons year-on-year, representing a growth rate of 52.31%. In July alone, exports amounted to 44,000 tons, down 4000 tons months-on months but up 12,300 tons year-on-year, with a net export of 15,200 tons-continuing the net export trend since June. Regarding export composition, primary forms of other PS and modified PS were the main export categories, accounting for over 90% of total exports. In terms of market distribution, exports were highly concentrated in emerging economics, with southeast Asia as the core market. Vietnam, Thailand, the Philippines, and Indonesia showed strong procurement demand, collectively accounting for more than 25% of total exports. Meanwhile, markets in central Asia, Africa, Eastern Europe, and Latin American expanded simultaneously, with steady order growth from countries such as Kazakhstan, Poland, Russia, and south Africa, gradually forming a diversified export structure.
Second. Import and Export Operations of ABS Plastic
From January to July 2026, the structural optimization of ABS industry trade continued steadily, primarily reflected in a gradual decline in net import dependency.
In terms of imports, from January to July, China's cumulative ABS imports reached 429,300 tons, down by 74,600 tons year-on-year, a decrease of 14.80%. The import structure shows significant differentiation: general-purpose injection-grade ABS imports have continued to decline, highlighting the effectiveness of domestic substitution. Meanwhile, high-end modified ABS grades—such as those with high flowability, weather resistance, flame retardancy, and ultra-high impact strength—as well as specialty grades remain highly dependent on imports. These products currently constitute the core segment of ABS imports and are also the main reason why the domestic ABS trade structure is difficult to reverse quickly. Import sources remain concentrated in East Asia, with Taiwan, South Korea, and Japan being the primary suppliers, indicating a high level of supply concentration, while the Middle East and Southeast Asia serve as supplementary sources.
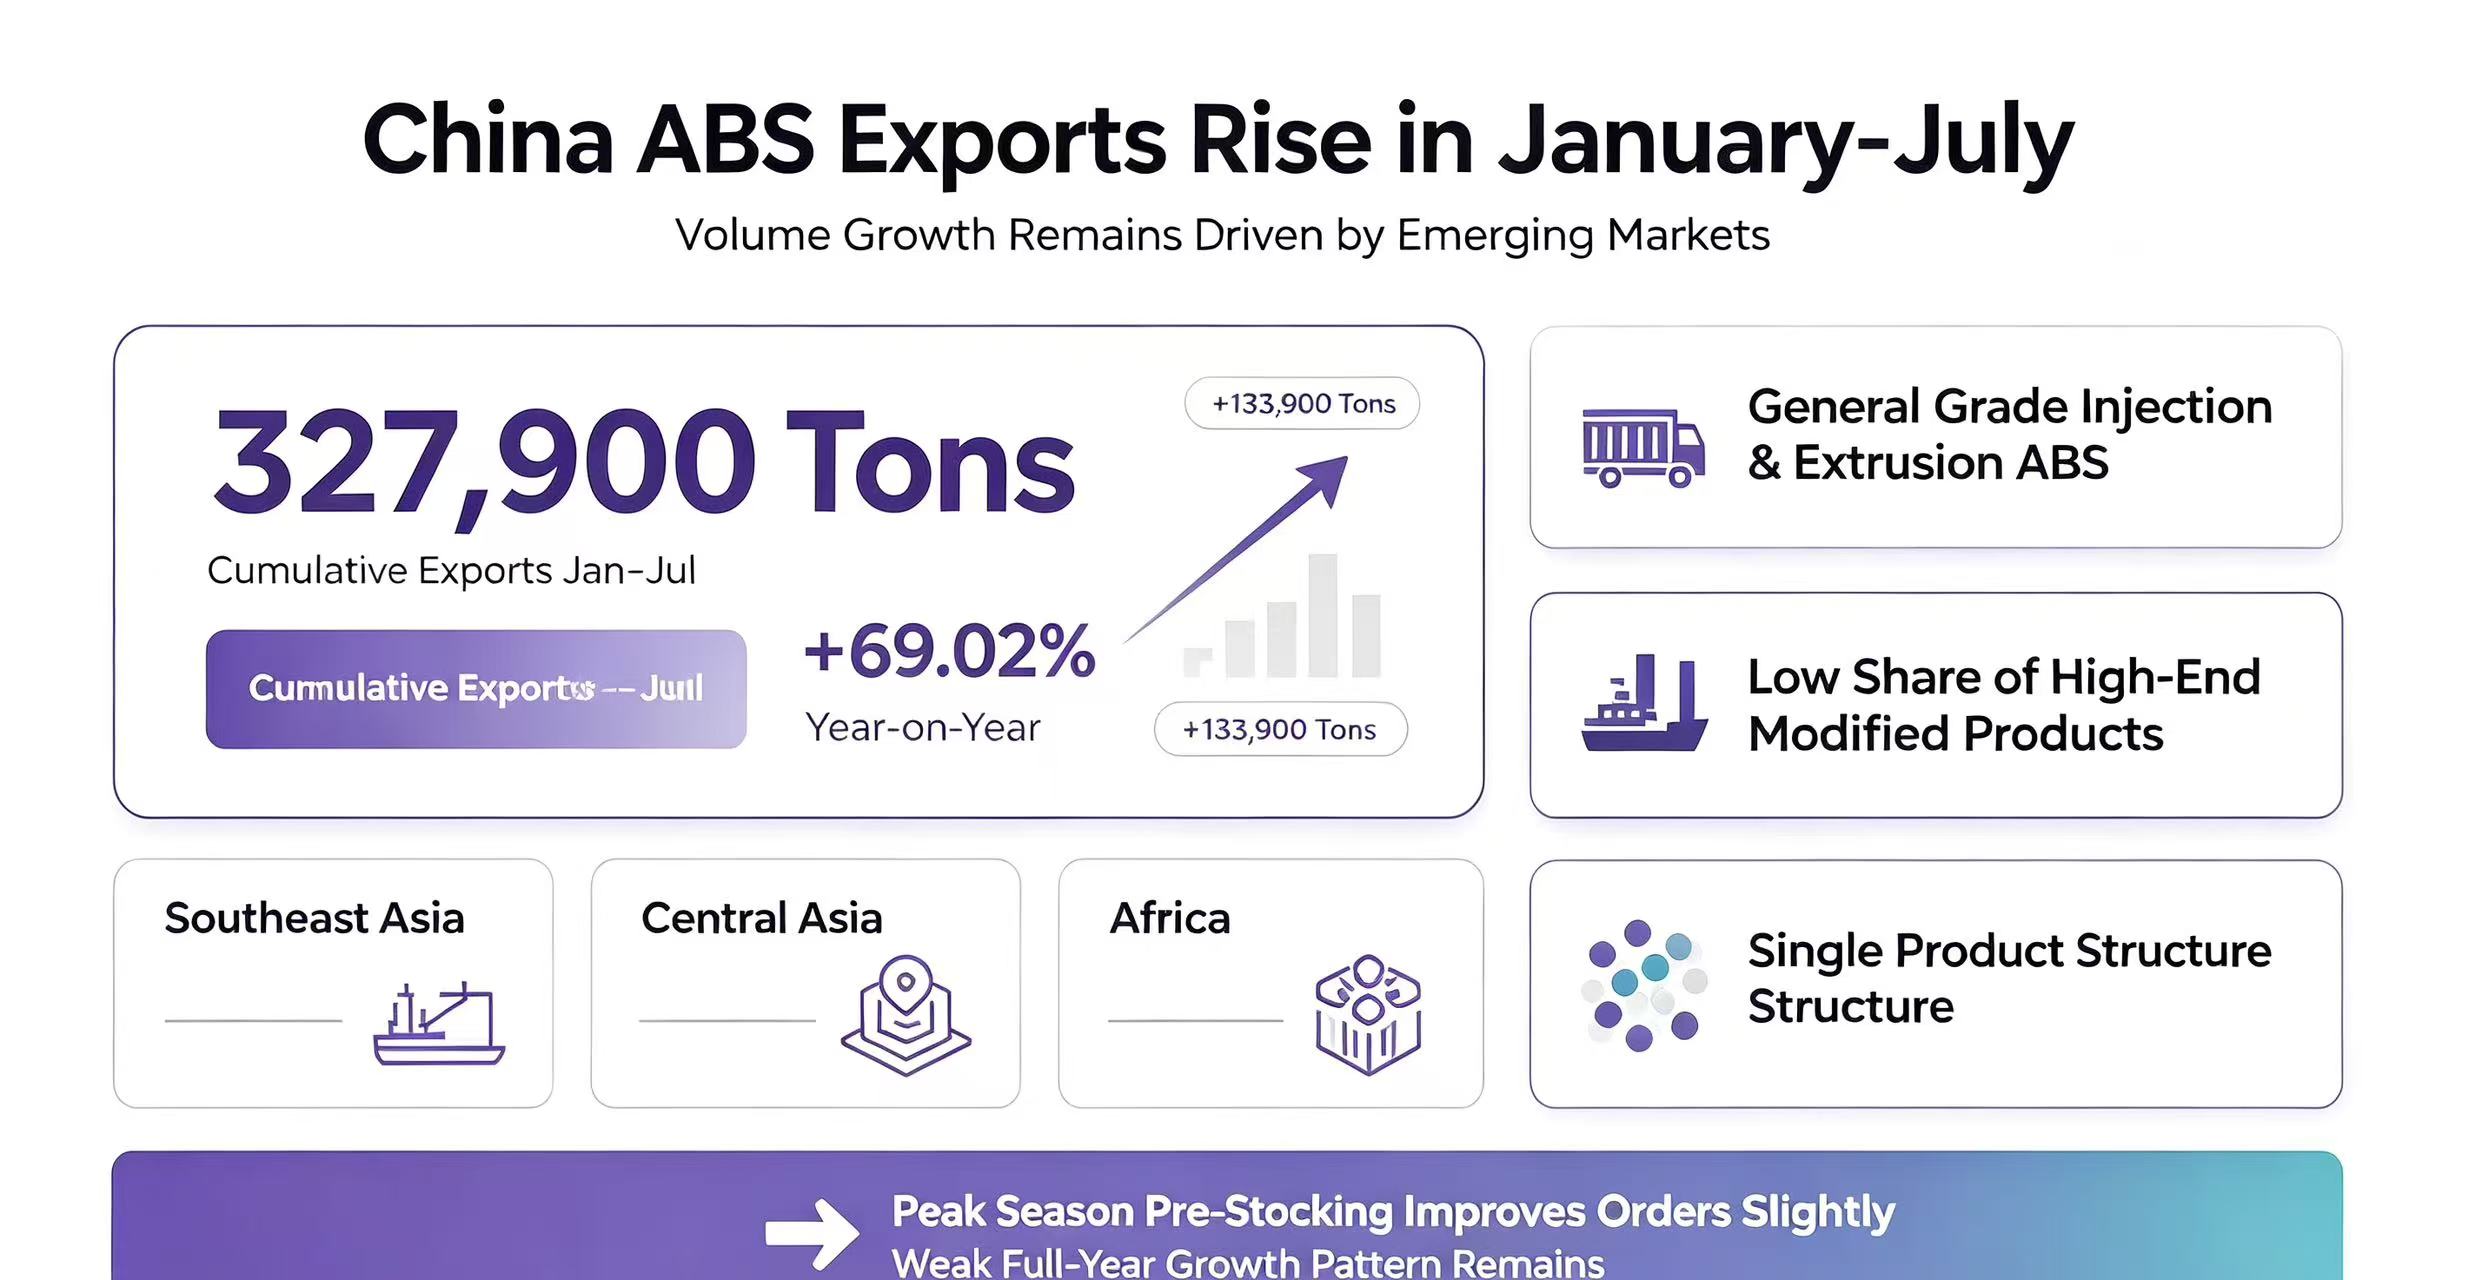
In terms of exports, from January to July, China's cumulative ABS export volume reached 327,900 tons, an increase of 133,900 tons year-on-year, representing a growth rate of 69.02%. The export market primarily consisted of neighboring emerging economies, with Southeast Asia, Central Asia, and Africa serving as key destinations for mid-to-low-end markets. The products exported were mainly general-purpose injection and extrusion-grade ABS, while high-end modified grades accounted for only a negligible share. The export product structure remains limited and low in added value, indicating that overall export competitiveness is still in a weak recovery phase. From July to August, the industry entered the pre-season inventory buildup period during the traditional peak season, leading to a slight rebound in export orders; however, the overall improvement was modest and did not alter the pattern of weak annual growth.
Third. Overall comparison and summary of future market trends
From January to July 2026, the import and export patterns of ABS and PS plastics showed a clear divergence: PS, benefiting from domestic capacity substitution and global supply chain advantages, reserved its trade status, with exports becoming the core growth driver for the industry, in contrast,ABS, constrained by reliance on imported high-end products and weak overseas demand, has yet to break through its traditional trade structure.
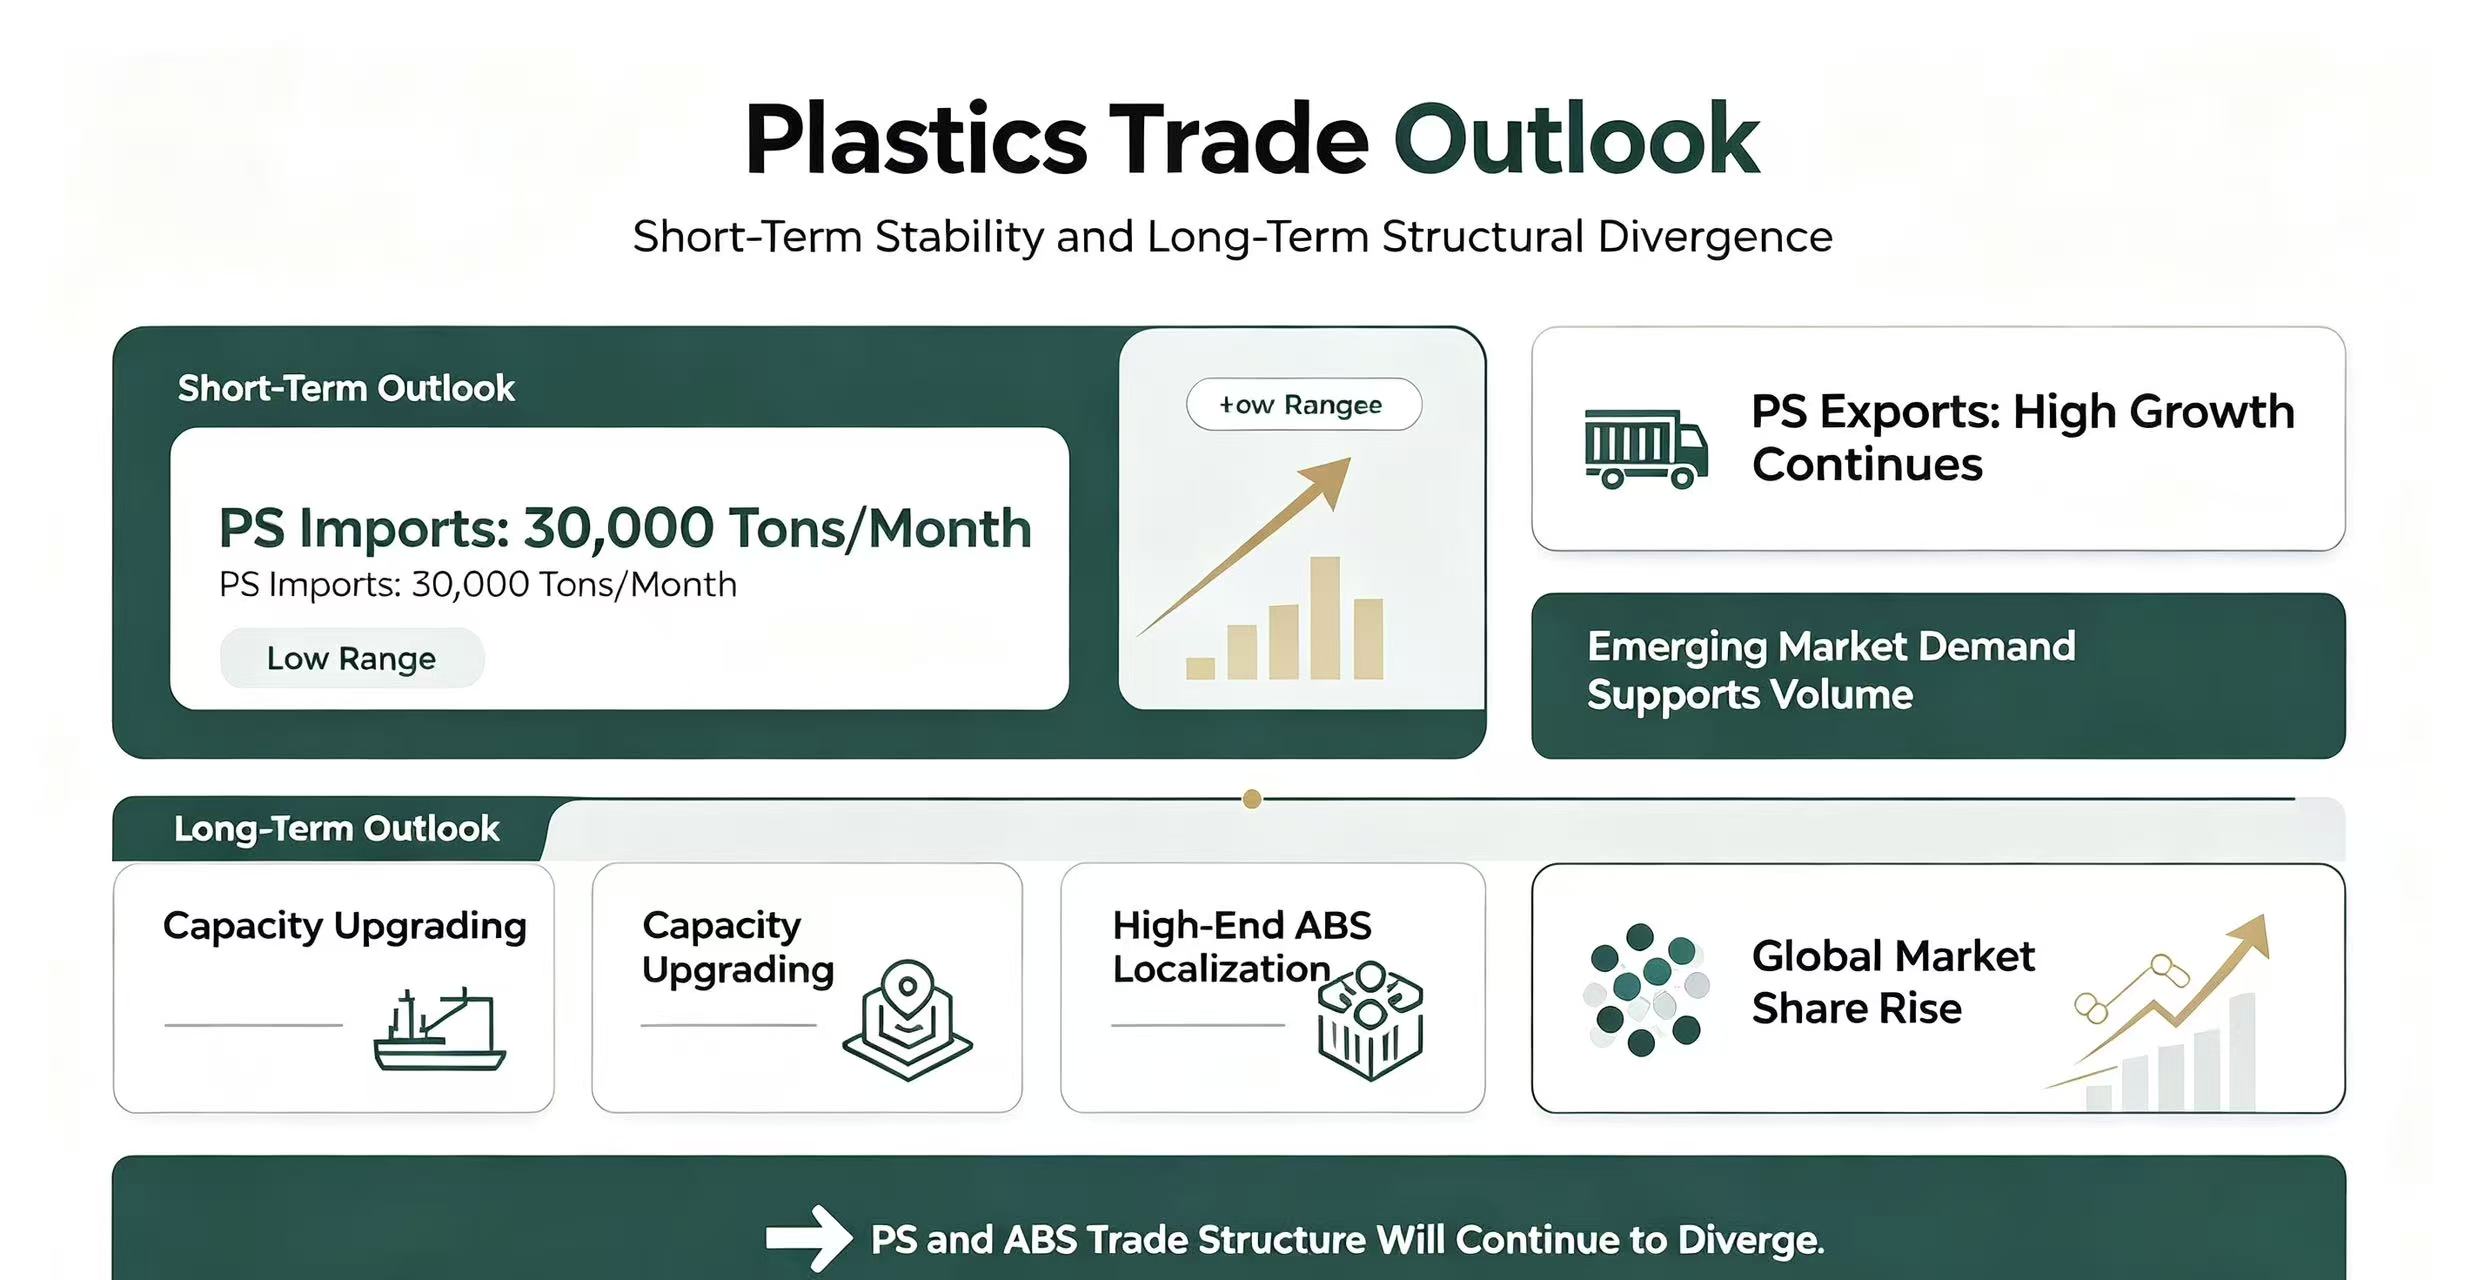
Looking ahead, in the short term, PS imports will remain at a low level of around 30,000 tons per month, while export growth is expected to continue, supported by sustained demand from emerging markets. ABS imports and exports are likely to maintain stable operation, import demand will remain supported by essential needs, while export performance is unlikely to see significant improvement. Overall, the pace of trade structural optimization for ABS will be slower than that for PS. In the long term, as domestic general-purpose plastic capacity continue to upgrade, the localization of high-end ABS will accelerated and export markets will expand further. The structural divergence in imports and exports between these two product categories will persist, leading to a steady increase in the global market share of domestically produced plastics.

Your service intention information has been submitted to the platform, we will contact you within 2 working days, please check your email. Thank you.
CPC Index, fully known as China Plastic City Raw Material Price Index, is an important tool to reflect the price trend of plastic raw materials in China Plastic City. The launch of this index aims to provide a reliable reference basis for the majority of plastics industry enterprises to help them better grasp market trends and formulate business strategies.
As the "Industrial Information Operation Situation Index Enterprise" designated by the Ministry of Industry and Information Technology, our company is well aware of the industry's urgent need for accurate and timely plastic price information. Therefore, we officially launched the plastic index in June 2011, providing a professional and authoritative price reference for the majority of plastic enterprises.
The average price is an average price obtained through scientific calculation by our platform according to the price of various plastic products in the whole Chinese market. This average price not only reflects the reference price level of the market as a whole, but also is calculated based on the specific price situation of each sub-brand. In short, the average price is a comprehensive indicator, which reflects the average price level of various plastic products in the Chinese market during a certain period.
By viewing the average price of the market, you can understand the average price trend of various plastic products in a specific period. This helps you to better understand the market dynamics, supply and demand of various products and market competition.
The market reference price refers to the accurate and timely quotation provided by several large traders or agents of a certain brand in China Plastics City. We take the reference price of the brand in Yuyao area on the same day according to the price provided by them. The firm that provides the price is listed as the index gathering firm.
Through the market reference price, you can understand the average price level of the current market, so as to better formulate purchasing, sales and other business strategies. At the same time, the market reference price is also an important basis for users to analyze and forecast the market, helping them grasp the market trend and find business opportunities.
The reference price rise and fall list is a tool to rank the price rise and fall of various categories of plastic products under the market reference price. It tracks and compares the price changes of products under various categories of symbols in different time periods such as week, month and year, and then selects the top 20 with the highest price increase or the top 20 with the highest price decrease to form the price rise list and price fall list respectively.
The reference price rise and fall list provides a practical reference for practitioners in the plastics industry, helping you quickly capture the most volatile products in the market, and providing strong data support for your decision.